


Author: Mark
Transactions with Unfriendly-State Persons in 2026
Updated: August 2026
Introduction: from the first decree to a comprehensive system
Regulation of transactions involving foreign persons from unfriendly states has evolved rapidly: from the basic approval regime introduced in September 2022 to a complex system of restrictions, conditions and court positions that exists by mid-2026.
The starting point was Presidential Decree No. 618 dated 8 September 2022. It introduced a special procedure for transactions involving participatory interests in Russian limited liability companies, where such transactions directly or indirectly establish, change or terminate rights of ownership, use or disposal of such interests, or other rights allowing a person to determine the management terms of such companies. Since then, transactions involving persons from unfriendly states have required approvals from the Government Commission for Control over Foreign Investments in the Russian Federation. An exception was made only for certain financial and fuel-and-energy sector organisations.
On 19 September 2022, the Russian Government approved the procedure for obtaining such approvals (Resolution No. 1651). On 13 October 2022, the Ministry of Finance published clarifications specifying the types of transactions covered by Decree No. 618: from transfers of participatory interests and acquisition by an LLC of its own interest to pledges, trust management, shareholders’ agreements and even simple partnership agreements. In total, 13 categories were listed, plus “other transactions”.
In parallel, Decree No. 737 dated 15 October 2022 introduced additional restrictions on payments upon reduction of charter capital, liquidation of LLCs and bankruptcy procedures, setting a threshold of RUB 10 million per month. If the threshold is exceeded, a type “C” special account or a permit from the Ministry of Finance is required.
From late 2022, the conditions for obtaining approvals began to tighten. Initially, according to Extract No. 118/1 dated 22 December 2022, the requirements included an independent valuation, a discount of at least 50% to market value, KPIs for new owners and an alternative: payment by instalments for 1-2 years and/or a voluntary contribution to the budget of at least 10% of the transaction amount. By March 2023, that alternative had disappeared: the contribution became mandatory.
By August 2026, the analysis of a transaction with a foreign element is built around the specific operation, rather than around the general label “unfriendly counterparty”.
- For participatory interests in LLCs, Decree No. 618 applies.
- For loans, financial instruments and, from 1 June 2026, bank deposits, Decree No. 95 and Decree No. 81 apply.
- For corporate payments, Decree No. 254 applies.
- For real estate, Decree No. 81 applies.
- For certain intellectual property payments, Decree No. 322 applies.
- The rules of the Government Commission, currency control requirements, withholding tax, double tax treaty issues and transfer pricing aspects also remain relevant.
Several important sources and clarifications were added in 2026:
- Thematic Review of the Supreme Court of the Russian Federation No. 8/2026 dated 17 June 2026;
- Official Clarifications of the Ministry of Finance No. 5 dated 1 July 2026;
- Government Resolution No. 888 dated 15 July 2026;
- extension of the Bank of Russia restrictions on foreign transfers until 7 December 2026; and
- Federal Law No. 319-FZ dated 4 August 2026 on judicial termination of certain buyback rights.
Map of new points of focus as of August 2026
| Source | What it changes | Practical takeaway |
|---|---|---|
| Supreme Court Thematic Review No. 8/2026 | Court positions on real estate, strategic assets, payments under Decree No. 95, payment splitting, assignments and payments to rights holders. | A transaction or payment may be void not only because an approval was missing, but also because the structure was designed to circumvent the special regime. Formal compliance with thresholds does not protect against abuse-of-right findings. |
| Ministry of Finance Clarifications No. 5 | Two narrow exceptions from the Decree No. 618 procedure: certain amendments to LLC charters concerning management bodies, and cancellation of an undistributed or unsold interest held by the company itself with a charter capital decrease. | These exceptions cannot be extended by analogy to any change of control, corporate agreement, option or redistribution of participant rights. |
| Government Resolution No. 888 | Amendments to the rules for issuing approvals of the Government Commission; part of the provisions apply until and including 30 April 2029. | Before filing an application, companies should check not only the public document package, but also new closed elements of the approval route. |
| Decree No. 377, subsequent Bank of Russia clarification and Decree No. 550 | Decree No. 95 and the type “C” special account regime were extended to bank deposits; the Bank of Russia separately clarified deposit extension and performance of payment obligations. | A deposit of a foreign person from an unfriendly jurisdiction should be routed through type “C” special accounts where the special regime applies. |
| Bank of Russia information dated 1 June 2026 | Restrictions on transfers abroad for non-residents from unfriendly states remain in force until and including 7 December 2026. | For branches and representative offices of foreign companies, transfers of funds to the head office remain restricted. |
| Federal Law No. 319-FZ dated 4 August 2026 | A law was adopted allowing judicial termination of a foreign investor’s right to buy back a previously sold Russian asset. | A buyback right should no longer be treated as an automatic old option. The date of disposal, investor conduct, price, investments by the current owner and the court procedure matter. |
Evolution of exit conditions: from 2022 to 2026
To understand the current requirements correctly, it is critical to see how the conditions for obtaining approvals for transactions with participatory interests in LLCs involving persons from unfriendly states have tightened over time.
December 2022: initial conditions (Extract No. 118/1)
The Government Commission subcommittee set the first conditions for issuing approvals:
- an independent market valuation of the assets;
- sale of assets at a discount of at least 50% to market value;
- establishment of key performance indicators (KPIs) for new owners;
- payment by instalments for 1-2 years and/or a voluntary budget contribution of at least 10% of the transaction amount.
At the same time, conditions for dividend payments were formulated for the first time where payments exceeded RUB 10 million per month or the equivalent in foreign currency under Decrees No. 95 and No. 254: dividends of no more than 50% of net profit for the previous year, retrospective analysis of previous distributions, willingness of foreign participants to continue commercial activity in Russia, positions of federal executive bodies, quarterly KPIs and quarterly payments subject to KPI performance.
March 2023: tightening (Extract No. 143/4)
Material changes were introduced: the budget contribution became mandatory; two contribution options were introduced; applicants were recommended to provide expert opinions from self-regulatory organisations of appraisers together with valuation reports; and a list of appraisers recommended for market valuation was published.
July 2023: systematisation (Extract No. 171/5)
The document repealed protocols No. 118/1 and No. 143/4 and introduced a comprehensive package of conditions for LLC interest transactions: valuation by a recommended appraiser, an SRO expert opinion, a discount of at least 50%, a voluntary budget contribution within three months after the transaction, KPIs for buyers, buyback at market value on the exercise date with economic benefit for the resident, settlement through a type “C” account or other permitted routes, and other required approvals.
For dividends, the July 2023 criteria included no more than 50% of net profit for the previous year, retrospective analysis, readiness to continue activity in Russia, assessment by federal authorities, KPIs and quarterly payments.
August 2023: easing for dividends (Extract No. 182/5)
Approvals for dividend payments could be issued without complying with the standard conditions where investments had been made into the Russian economy after 1 April 2023, for example expansion of production or development of new technologies, and within the amount of such investments.
October 2023: further tightening (Extract No. 193/4)
The voluntary contribution was increased to 15% of market value. The application form was also updated: beneficial owners of all transaction parties, not only the applicant, had to be disclosed.
January 2024: procedural clarifications (Resolution No. 40)
Government Resolution No. 40 dated 22 January 2024 established mandatory inclusion of an independent valuation report from a recommended appraiser, mandatory indication of KPIs and their target values for buyers, monitoring of KPI achievement by federal executive bodies and/or the Bank of Russia, and exceptions from valuation and KPI requirements for transactions within the same group and for transactions between persons connected with unfriendly states.
October 2024: new tightening of conditions (Extract No. 268/1)
The key conditions for approvals in exit transactions became: a voluntary budget contribution of 35% of market value, paid as 25% within one month after closing, 5% within one year and 5% within two years; a mandatory discount of at least 60% to market value; and Presidential consent where the asset value exceeds RUB 50 billion. These conditions apply both to future applications and to applications already filed but not yet considered.
July-August 2026: two developments moving in different directions
1. Ministry of Finance Clarifications No. 5: approval of the Government Commission is not required for two types of action: amendment of an LLC charter regarding formation, competence or termination of management bodies, provided participant rights and actual control are not changed; and change of a participant’s interest as a result of cancellation of an undistributed or unsold interest held by the LLC itself with a corresponding decrease of charter capital.
2. Federal Law No. 319-FZ dated 4 August 2026: the law introduced a mechanism for judicial termination of buyback rights of foreign investors from unfriendly states in relation to previously sold Russian assets. The Arbitrazh Court of the Moscow Region may deny exercise of such buyback right where, among other factors, the former owner publicly supported anti-Russian sanctions or discredited the Russian Armed Forces, the sale was non-market in nature, or the new owner made significant investments without which the asset could have stopped operating. A claim may be filed before the investor demands the buyback. If the right is terminated, the investor may have a separate compensation route, although the amount and availability of compensation depend on the circumstances.
Verification matrix: operation, approval, payment and documents
When assessing feasibility and the required steps for a transaction, the starting point should not be the general question of an unfriendly jurisdiction. The starting point should be a map of the specific operation.
The same foreign group may simultaneously hold an interest in a Russian LLC, a loan, a licence agreement, a service agreement, a branch and real estate. Each element may have its own regime, payment route and document set.
| Operation | Applicable regime | Approval or exception | Payment issue |
|---|---|---|---|
| Sale of an interest in a Russian LLC by a foreign participant from an unfriendly state | Decree No. 618, Government Commission rules, Resolution No. 888 | Exceptions must be confirmed separately and should not be extended by analogy. | The transaction price, source of buyer funds, ability to transfer funds to the foreign seller and bank documents are checked separately. |
| Change of LLC management bodies | Ministry of Finance Clarifications No. 5 to Decree No. 618 | May fall outside Decree No. 618 if the amendment concerns only company bodies and does not change participant rights or actual control. | Usually no payment arises, but the management change itself may be relevant for control analysis. |
| Cancellation of an interest held by the company itself | Ministry of Finance Clarifications No. 5, Article 24 of the LLC Law | An exception is possible if the statutory conditions and charter capital decrease are strictly observed. | Usually not a payment to a foreign participant, but the history of the interest and settlements should be checked. |
| Dividend payment to a foreign participant | Decree No. 254, Decree No. 95, subcommittee criteria | A corporate distribution resolution requires an additional check of the special procedure and possible approval. | Account, bank, currency, withholding tax under the current double tax treaty status, beneficial ownership and corporate payment documents must be determined. |
| Loan or interest repayment to a foreign creditor | Decree No. 95 and Supreme Court Review No. 8/2026 | The threshold and performance procedure are checked based on the aggregate obligations; splitting payments does not automatically make the structure safe. | Monthly performance volume, interest, assignments, set-offs and the ultimate beneficiary are relevant. |
| Bank deposit of a foreign person | Decree No. 377, Bank of Russia clarifications and Decree No. 550 | From 1 June 2026, Decree No. 95 was extended to deposits. Deposit extension should be distinguished from payment of interest and return of principal. | Interest payment or return of the deposit may be a separately regulated performance of an obligation. |
| Licence payments, software, trademarks and technologies | Decree No. 322 and Supreme Court Review No. 8/2026 | A licence payment should be separated from services, expense compensation and hidden profit distribution. | A type “O” special account may be required; withholding tax and currency control are checked separately. |
| Intragroup services: IT, SAP, HR function, management and other services | Tax accounting, transfer pricing, currency control and bank review of the economic substance of the payment | Not every service payment requires a special route, but insufficient documentation materially increases tax and banking risk. | The payment should match the agreement, actually rendered services, period, benefit received and arm’s-length price level. |
| Transaction with Russian real estate | Decree No. 81, Rules No. 295, Supreme Court Review No. 8/2026 | Approval may be required even where the party is Russian-registered if it is controlled by a person from an unfriendly state. | Settlement, registration, source of funds and consequences of invalidity for circumvention of the special procedure are checked. |
| Closure of a branch or representative office of a foreign company | Accreditation rules, tax settlements and Bank of Russia restrictions on transfers | The procedure differs from liquidation of an LLC. | Transfer of remaining funds to the head office may fall under restrictions applicable to non-residents from unfriendly states. |
| Assignment of claim, change of creditor or set-off | Supreme Court Review No. 8/2026 and the regime applicable to the underlying obligation | Assignment to a friendly person or non-cash set-off does not automatically cleanse the obligation. | The court and the bank may look at the original creditor, assignment date, purpose of the structure and economic result. |
| Exercise of a buyback right for a Russian asset | Federal Law No. 319-FZ dated 4 August 2026, Decree No. 618 and the terms of the original approval | The official status of the law, judicial termination risk and need for new approval on the exercise date should be checked. | Buyback price, source of funds, payment to the foreign investor or Russian owner and bank route require separate review. |
Type “C” special accounts: practical guidance
Type “C” special accounts were introduced on 5 March 2022 by Presidential Decree No. 95 “On the temporary procedure for fulfilling obligations to certain foreign creditors”. Decree No. 737 dated 15 September 2022 also introduced additional restrictions on payments to foreign companies, in particular upon liquidation or reduction of charter capital; it entered into force on 15 October 2022.
When a type “C” account must be opened
A type “C” account is required for payments exceeding RUB 10 million, or the equivalent in foreign currency, in a calendar month to unfriendly foreign counterparties, and also to friendly foreign creditors if claims under the obligations were transferred to them from unfriendly creditors after 1 March 2022. This covers, among other things, aggregate debtor obligations under loans and credits, dividends and profit distributions by LLCs, financial instruments, derivative financial instruments, purchase of real estate from unfriendly individuals, and payments upon reduction of charter capital, liquidation or bankruptcy of resident legal entities, unless a permit is obtained.
Who opens the account, where and in which currency
The resident sends an application to a credit institution to open a type “C” account in the name of the foreign creditor; a bank account agreement is not required. The foreign creditor cannot open a type “C” account on its own initiative. The account is maintained in roubles, cannot be opened in foreign currency and cannot be opened with a foreign credit institution. A regular bank account opened earlier is not suitable, although certain securities accounts opened before 24 March 2022 may be used.
When the account is not required
The account is not required if the aggregate amount of all debtor obligations to all foreign creditors in a calendar month does not exceed RUB 10 million or the equivalent in foreign currency at the official exchange rate of the Bank of Russia as of the first day of the relevant month, or if an approval has been obtained. It is also not required if the obligation is performed to a person that is not “unfriendly”, subject to the relevant beneficiary and disclosure criteria.
What is permitted when using a type “C” account
A type “C” account opened for a non-resident at the request of one resident may be used by other residents to fulfil obligations to the same non-resident. Funds may be transferred to a type “C” account opened with a bank other than the resident’s servicing bank. Roubles may also be transferred between type “C” accounts of the same legal entity non-resident opened with different credit institutions. Residents are not restricted from using several type “C” accounts for different obligations in favour of one non-resident, or from using one type “C” account.
Restrictions and specific features
Funds on a type “C” account belong to the foreign creditor from the moment they are credited to the account and until an agreement is concluded with the foreign creditor. The bank may not close such account unilaterally merely because the foreign creditor has not contacted the bank. The resident may not dispose of or claim return of funds from the type “C” account, except in cases of erroneous crediting. Transfer from a type “C” account to another non-resident account, whether in Russia or abroad, is currently impossible without permission.
Permitted debits from a type “C” account
- payment of taxes, duties, fees and other mandatory budget payments;
- transfers for purchase of federal loan bonds;
- transfers to non-resident rouble accounts where permitted;
- other operations provided for by an approval;
- payment of fees to the authorised bank servicing the account.
LLC interests: where is additional approval required and where is it not?
Decree No. 618 covers transactions and operations that directly or indirectly establish, change or terminate rights of ownership, use or disposal of participatory interests in Russian LLCs, as well as other rights allowing a person to determine the management or business activity of the company.
The risk therefore arises not only in a classic sale of an interest. Options, pledges, trust management, corporate agreements, changes in ownership chains and transfer of management control also require review.
In October 2022, the Ministry of Finance specified the list of transactions requiring approval of the Government Commission: transfer of an interest in an LLC to participants or third parties; acquisition by an LLC of its own interest; exit of a participant from an LLC; transfer of an interest to an investment fund; agreement transferring powers of the sole executive body; corporate agreement; convertible loan agreement; pledge of an LLC interest; pledge management agreement; voluntary reorganisation; simple partnership agreement; trust management, agency or other agreement concerning rights attached to LLC interests; and other transactions.
Official Clarifications No. 5 dated 1 July 2026 are useful precisely because they are narrow. They exclude from Decree No. 618 certain LLC charter amendments concerning the formation, competence or termination of company bodies, and changes in a participant’s interest resulting from cancellation of an undistributed or unsold interest held by the company itself with a charter capital decrease under Article 24 of the LLC Law.
| Operation | Qualification in 2026 |
|---|---|
| Sale of an interest by a foreign participant | Requires analysis under Decree No. 618 and approval of the Government Commission. |
| Charter amendment concerning LLC bodies | May fall under the Ministry of Finance exception and not require special approval, provided participant rights and actual control are not changed. |
| Cancellation of a treasury interest | May fall under the Ministry of Finance exception if Article 24 of the LLC Law is strictly observed. |
| Intragroup change of owner of a Russian LLC | Not automatically exempt: indirect change of control may be relevant. |
Exit transactions: approval changes the economics, not only the timing
Extract No. 268/1 of the Government Commission subcommittee records the conditions generally applied to certain exit transactions by foreign investors: independent valuation, expert opinion, discount of at least 60% to market value, voluntary payment to the federal budget of at least 35% of market value, and Presidential consent where the asset value exceeds RUB 50 billion. The contribution is paid according to a schedule: 25% within one month after closing, 5% within one year and 5% within two years.
These criteria should not be presented as a direct universal prohibition on selling an asset for more than 40% of its market value. However, in the financial model of an exit transaction they operate as a mandatory scenario to calculate. In addition to price and settlement terms, an approval may contain post-closing obligations for the new owner: preservation of activity, jobs, technologies, contracts, investment obligations, reporting to a competent authority or subsequent securities placement. Resolution No. 888 dated 15 July 2026 further confirms that interaction with the Government Commission remains procedurally complex.
Buyback after asset sale: an option is no longer a neutral right
On 4 August 2026, Federal Law No. 319-FZ was adopted, introducing judicial termination of certain buyback rights of foreign investors in relation to Russian assets.
The new mechanism focuses on assets disposed of after 22 February 2022 by a foreign investor connected with an unfriendly state to a Russian acquirer or another permitted acquirer. A buyback right may be terminated by court. Two groups of circumstances are particularly relevant: the conduct of the foreign investor after exit, and the economic terms of the transaction or subsequent actions of the acquirer.
For a transaction with a buyback right, it is not enough to analyse only the old option and its terms. The buyback price, market value evidence, investments by the current owner, corporate and operational obligations, public statements by the foreign investor, sanctions restrictions, correspondence with suppliers and rights holders should all be reviewed. If the right is terminated by court, the foreign investor may have a separate compensation route, but its amount and availability depend on the facts.
Dividends: careful procedure and detailed review are required
Payment of dividends to a foreign participant from an unfriendly state is not prohibited. However, adoption of a corporate resolution on profit distribution is not sufficient by itself: the entire procedure must be reviewed.
Decree No. 254 applies to corporate financial obligations, while performance of obligations to foreign creditors and special accounts are linked to Decree No. 95. For amounts above RUB 10 million per month, or the equivalent in foreign currency, approval of the Government Commission or use of a type “C” special account is required. According to the Supreme Court’s 2026 clarification, artificial splitting of amounts without economic justification may be treated as a violation.
When dividend approvals are considered, the subcommittee usually takes into account the amount of the payment, with a general benchmark of up to 50% of net profit for the previous year, dividend history, continuation of the Russian company’s activity, KPIs and investments by the foreign participant into the Russian economy after 1 April 2023.
Other material points should not be forgotten: proper corporate documents, careful withholding tax analysis in light of the current double tax treaty status with the foreign participant’s jurisdiction, proof of tax residence and beneficial ownership of income, the bank’s currency control requirements and subsequent reporting.
Loans, deposits, assignments and set-offs: courts look at the economic result
Under Decree No. 95, the special procedure applies to obligations under loans, credits and financial instruments owed to certain foreign creditors where the RUB 10 million calendar-month threshold is exceeded. In Thematic Review No. 8/2026, the Supreme Court specifically noted the risk that a payment made without observing Decree No. 95 may be void, and the risk of artificial payment splitting.
The key conclusion of paragraph 4 of Supreme Court Review No. 8/2026 is that formal division of payments into tranches below RUB 10 million with the aim of circumventing the special settlement procedure constitutes abuse of rights. If the totality of operations indicates an intention to bypass Decree No. 95, such actions may be treated as void under Articles 10 and 168 of the Russian Civil Code.
The economic purpose of the operation, total amount of aggregate obligations, control of payment recipients by unfriendly jurisdictions and interconnection of all payments are now critical. An assignment of claim after 1 March 2022 also does not automatically “cleanse” the obligation. The Supreme Court allows analysis of the original creditor, assignment date, nature of the underlying obligation and purpose of the structure, including cases involving a type “O” account under Decree No. 322.
Intragroup services, royalties and transfer pricing: type “C”, type “O” or neither?
Payment for genuine services of a foreign parent company does not automatically become a loan or dividend distribution. However, in 2026 such payment should pass at least four independent tests: economic rationale of the expense, tax deductibility and proper documentation, bank review and currency control, and transfer pricing conditions.
For IT, SAP, HR, procurement, management support and shared service centre charges, an agreement and an act are not enough. Supporting materials are needed: tickets, reports, methodologies, settings, correspondence, cost allocation calculations and confirmation of economic benefit for the Russian company.
Licence payments, software, trademarks and technology payments should be separated from ordinary services or goods payments. For certain obligations to foreign rights holders, Decree No. 322 may apply and a type “O” special account may be required. At the same time, the Supreme Court in Review No. 8/2026 does not support a purely mechanical approach based only on the rights holder’s jurisdiction; the factual circumstances and conduct of the rights holder should be analysed.
Real estate: Russian registration of the parties does not close the control issue
One of the important positions of the Supreme Court in 2026 concerns real estate. In Review No. 8/2026, the court stated that a sale and purchase agreement for real estate located in Russia, entered into with a Russian person controlled by a foreign person from an unfriendly state, may be void if concluded without approval of the Government Commission. For a Russian subsidiary with a foreign participant from an unfriendly state, this means that approval may be required even where the buyer is Russian.
Branches and representative offices: what restrictions apply?
A branch or representative office of a foreign organisation is not a Russian legal entity. It has no participatory interests to sell and no dividends that a Russian company distributes to its participant. However, restrictions apply to the transfer of remaining funds to the head office, including upon closure of accreditation. These restrictions are currently preserved until 7 December 2026, and further extension should be expected.
Liquidation of an LLC: specific features for companies with unfriendly foreign participation
When deciding on liquidation, several general rules should be kept in mind. Liquidation is not a quick process and may take up to one year; this period may be extended by court for another six months. From the moment the liquidation decision is adopted, the powers of the current general director terminate and management passes to the liquidator or liquidation commission. Preparatory work is needed: before liquidation, the company should ensure that it has no outstanding tax debts or supplier/customer debts. HR work should be planned and employment contracts terminated. Documents should be transferred to an archive, with certain documents subject to mandatory retention for at least 75 years or longer depending on the type. A tax audit covering up to the previous three years may occur.
In addition to these general standards, companies with foreign participation from unfriendly states should take account of special points. Payments exceeding RUB 10 million per calendar month made by residents to persons from unfriendly states as a result of liquidation of resident legal entities are subject to a special procedure and should be made through type “C” accounts, unless permits are obtained from the Bank of Russia and the Ministry of Finance. Based on official Ministry of Finance clarifications, liquidation is not directly included in the list of transactions under Decree No. 618 and formally does not require approval of the Government Commission. However, in practice, including under explanations of authorised bodies and notarial chambers, certification of a liquidation application may be refused without such approval. This should be considered at the planning stage.
“Dormant” mode of a company: what to know
Many companies undergoing restructuring go through a phase of reduced activity, often referred to as “dormant” mode. Such phase frequently precedes liquidation. “Dormant” mode is not an official legal term. It means transferring the company into an inactive state, i.e. ceasing commercial activity while preserving the legal entity.
What should be considered when moving a company into dormant mode?
- the company still has to file tax returns, including nil returns, and pay taxes;
- the company still needs a general director;
- the company still needs a registered address;
- liquidity should be planned for minimum ongoing payments: accounting and tax support, software, salary and rent.
Is documentary formalisation required?
No formal document is required to introduce “dormant” mode. However, in some cases participants may adopt a decision to suspend activity. Such decision may be presented to authorities upon request or used as the basis for an internal order.
Should state authorities be notified?
As a general rule, no special notice of dormant mode is required. However, other statutory notifications may be required depending on the facts. For example, if staff reductions are planned, the employment service should be notified two months in advance.
Should counterparties be notified?
As a general rule, no special notices to counterparties are required. However, if the company has open obligations, counterparties should be informed about planned cessation or reduction of commercial activity. Dormant mode does not release the company from contractual obligations or liability for breach.
What about employees?
Dormant mode is not a ground for non-payment of salaries or dismissal. HR matters should be planned carefully. Depending on the circumstances, the company may introduce downtime, reduce staff or terminate employment contracts by another lawful route, but the process should be planned to avoid employment law risks.
Practical scenarios
1. Sale of a Russian LLC to management with a buyback option
Situation. A German participant sells 100% of the interests in a Russian LLC to the general director. The transaction is made at a 60% discount to market value in line with current requirements. A buyback option within two years is included. The seller expects to regain the asset after the geopolitical situation stabilises.
The transaction falls under Decree No. 618 and requires Government Commission approval. An independent valuation by a recommended appraiser and an SRO expert opinion are needed. The discount should be at least 60%; the voluntary contribution is 35% of market value with the 25% / 5% / 5% schedule. If the asset value exceeds RUB 50 billion, Presidential consent is required. The buyer should assume KPIs, and the buyback option should be limited to no more than two years from the initial transaction and priced at market value on the exercise date.
New in 2026: Federal Law No. 319-FZ allows the new owner to terminate the seller’s buyback right through court if the statutory conditions are met. The option should therefore not be treated as a guaranteed return of the asset.
2. Dividend payment to a Dutch participant: amount below RUB 10 million
Situation. A Russian subsidiary LLC has a small profit for 2024. A Dutch participant from an unfriendly jurisdiction requests dividends of RUB 6.7 million.
- The payment is below RUB 10 million as a one-off payment, so additional approval is generally not required.
- The foreign participant should provide a proper corporate resolution, tax residence certificate and beneficial ownership confirmation.
- The current double tax treaty status should be checked and withholding tax calculated.
- Not all banks can execute a payment to an unfriendly foreign jurisdiction; the payment route may require separate work.
- All documents should be provided to the bank for currency control.
3. Dividend payment to a German participant: amount above RUB 10 million
Situation. A Russian subsidiary LLC has significant accumulated profit for 2024. A German participant requests dividends of RUB 50 million.
- The amount exceeds RUB 10 million.
- Artificial splitting of the amount into smaller payments creates invalidity risks under the Supreme Court’s 2026 clarifications.
- The amount above RUB 10 million per month may be credited to a type “C” special account or require Government Commission approval.
- Corporate, tax residence and beneficial ownership documents are still required.
- The current double tax treaty status and withholding tax should be checked.
- The bank payment route and currency control package should be prepared in advance.
4. Loan repayment in monthly instalments of RUB 9 million
Situation. A Russian LLC owes RUB 80 million under a loan to its Swiss parent company. It plans to repay the debt in equal monthly instalments of RUB 9 million to avoid formally exceeding the RUB 10 million threshold under Decree No. 95 and avoid opening a type “C” account.
The formal monthly limit for each individual payment does not provide immunity. The Supreme Court stated that artificial splitting of payments to circumvent the special settlement procedure may constitute abuse of rights and make payments void. The court will assess the aggregate monthly performance, interest, assignments, set-offs and ultimate beneficiary. The recommendation is not to rely on formal splitting; if the overall obligation exceeds RUB 10 million per month, a type “C” account or Government Commission approval should be considered, and the payment structure should have real economic justification.
5. Single payment for management, IT, SAP, HR function and brand
Situation. A Russian subsidiary makes a monthly payment to its foreign parent company for a bundle of services: management support, SAP maintenance, HR outsourcing, royalties for trademark and software use. Everything is combined in one agreement and one payment.
The risk arises not because a service is always equal to dividends, but because a single mixed payment makes it difficult to comply with different regimes applicable to its components. IT/SAP requires proof of actually rendered services such as tickets, reports and settings. Royalties may fall under Decree No. 322 and potentially require a type “O” special account. Management services require functional analysis, specific documentation and an economic rationale test. A bank and tax inspectorate see the payment purpose and documents, not the group’s internal business logic. Weak documentation may lead to requalification and additional tax and penalties.
6. Liquidation of an LLC with a sole participant from an unfriendly state
Situation. A company wholly owned by a UK holding decides to liquidate. Charter capital is RUB 15 million and there are funds on the accounts for settlements with the participant.
Liquidation will take at least one year and may be extended by court. A liquidator should be appointed, inventory and creditor settlements should be performed, documents transferred to archive and a tax audit may occur. For the foreign participant, distribution of funds upon liquidation falls under Decree No. 737 and Decree No. 95. A type “C” account or a permit from the Ministry of Finance is required. Although the Ministry of Finance has clarified that liquidation is not directly listed under Decree No. 618, many notaries may refuse to certify liquidation applications without Government Commission approval, creating a procedural deadlock that should be planned for.
Frequently asked questions
1. Is Government Commission approval required for any transaction with foreigners from unfriendly states?
No. First, the type of operation, status of the parties, subject matter and payment should be determined. Ordinary commercial transactions, such as sale of goods or services, generally do not require additional approvals. However, operations that change control or management rights are likely to require approval.
2. Can an LLC charter be amended without Government Commission approval?
Yes, provided the amendment does not change the ownership structure.
3. Can a new director be appointed without Government Commission approval?
Yes. However, since 2024 this procedure requires mandatory participation of a Russian notary.
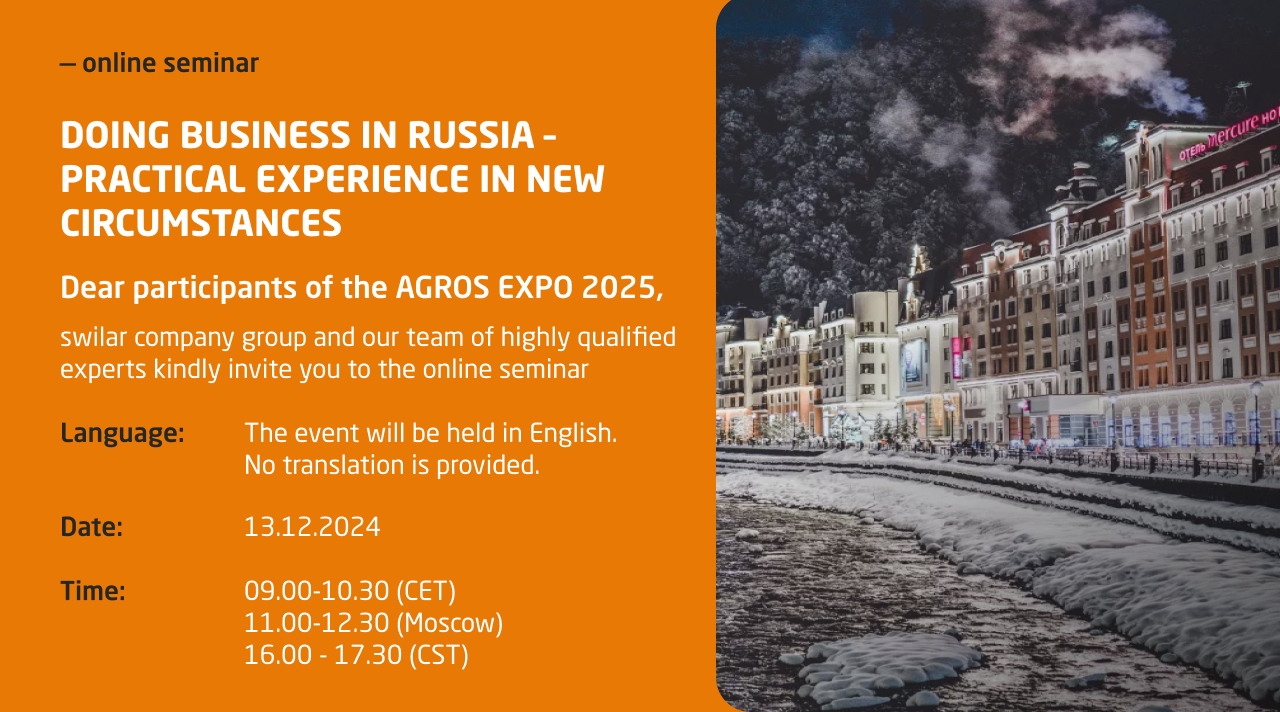
Online seminar 13.12.2024: Doing Business in Russia – Practical Experience in New Circumstances
PROGRAM
Detailed reviews and Q&A session with experienced experts on the following topics
1. Doing business in Russia
Legal, tax, HR and migration issues. Basics.
2. Overview on bank transaction with Russia
SWIFT, currency exchange and other.
3. Practical experience of foreign companies in Russia
FAQ in the regular business processes.
Account of a Russian LLC abroad
In the context of ongoing difficulties with international payments, many companies have found it necessary to open an account in a foreign bank.
However, it is important to remember that opening a bank account in another jurisdiction imposes a number of additional obligations on the company, including the submission of necessary reports and notifications.
In our review, we will look at how not to violate the law in this situation and how to avoid penalties.
Let’s take a step-by-step look at what a company has to do to comply correctly with all requirements.
1. Notify the Federal Tax Service of Russia.
It is necessary to notify the Federal Tax Service in the following cases:
- opening a bank account outside the Russian Federation;
- closing such an account;
- changing the account details.
All Russian organizations are required to submit the corresponding notification. (Part 2, Part 8 of Art. 12 of the Law No. 173-FZ). The notification should be sent to the tax authority at the location of the organization in the form approved by the Order of the Federal Tax Service of Russia dated 26.04.2024 N SD-7-14/349@, within one month from the date of opening (closing) an account or changing the details, respectively (Part 2 of Art. 12 of the Currency Control Law).
Two forms have been approved: one is for opening and closing an account (Appendix N1), the other is for changing the details of this account (Appendix N2).
The notification can be submitted to the tax authority on paper (in person, through a representative, by registered mail) or in electronic form via telecommunication channels (TCC) or through the taxpayer’s personal account (PA).
When making the first transfer to a bank account abroad, the organization needs to provide the Russian bank with a notificatio
on opening this account with a tax inspector’s note on its acceptance (Part 4 of Art. 12 of the Currency Control Law).
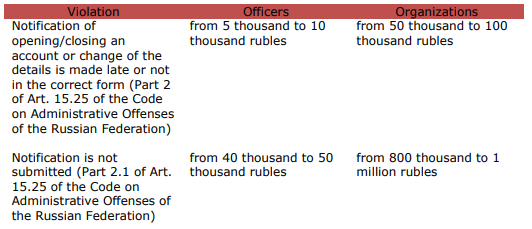
Failure to submit a notification about account or violation of the terms or procedure for submitting it may result in a penalty being imposed on the organization.
Their amounts are established in the Art. 15.25 of the Code on Administrative Offenses of the Russian Federation.
2. Report to the Federal Tax Service on flow of funds.
If a legal entity (resident of the Russian Federation) has foreign accounts, it has to submit a cash flow statement to the tax authority quarterly within 30 days after the end of the reporting quarter, attaching supporting documents: statements or other documents issued by the bank (Decree of the Government of the Russian Federation dated 28.12.2005 N 819 (as amended on 22.05.2024)).
If the documents are drawn up in a foreign language, the organization has to attach a translation into Russian, duly certified in accordance with the legislation of the Russian Federation (cl. 7 of the Rules for the Submission of Reports by Residents – Legal Entities).
The translation can be carried out by an employee of an organization or an organization engaged in translation activities, since the methods of translation are not limited by the law.
If necessary, at the request of the tax authorities, translation into Russian, notarized in accordance with the requirements of the legislation of the Russian Federation, shall be provided.
3. Comply with the currency legislation, in particular, carry out only legal currency transactions.
Contracts with non-residents, the amount of obligations for which exceeds the established threshold, namely, import contracts from 3 million rubles and export contracts from 10 million rubles, must be registered by an authorized bank of the Russian Federation.
The bank will assign a unique number to the contract (cl. 4.2, 5.5 of the Bank of Russia Instruction dated 16.08.2017 N 181-I (as amended on 09.01.2024).
When crediting export proceeds to an account abroad, it is necessary to provide to the authorized bank a certificate of currency transactions for settlements through an account abroad under accounting contracts, as well as provide a bank statement.
The term for providing a certificate of currency transactions for settlements through an account abroad is within 30 working days after the last day of the month in which such transactions were carried out.
4. Is it necessary to repatriate currency?
At present, the obligation to repatriate currency has only been retained for some companies.
From 16.10.2023 to 30.04.2025 inclusive, certain Russian exporters specified in the List approved by the Decree of the President of the Russian Federation dated 11.10.2023 No. 771, are required to credit to their accounts in authorized banks and sell proceeds in foreign currency on the domestic currency market of the Russian Federation within the established period and in the established amounts (cl. 1, 5 of the Decree of the Government of the Russian Federation dated 12.10.2023 No. 1681 “On measures for the implementation of the Decree of the President of the Russian Federation dated October 11, 2023 No. 771”).
The closed list consists of 43 groups of companies belonging to the sectors of the fuel and energy complex, ferrous and non-ferrous metallurgy, chemical and forestry industries, and grain farming. Exporters are notified of their inclusion in the list within 3 days by the Ministry of Economic Development of Russia.
For companies that are not on the closed list, the amount of foreign currency earnings subject to mandatory sale is currently 0%.
Therefore, if the organization is subject to the cancellation of repatriation, the terms for transferring export proceeds from the organization’s account opened abroad to a Russian bank are not established by regulation, i.e. such funds may remain on account abroad and these funds can be used, for example, for settlement of import or other contracts.
Contacts:
Natalia Safiulina
Nadezhda Kolomnikova
Other news

06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.

06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC

28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Changes in regulating transactions with persons from unfriendly countries
At this moment, for companies with Western participation, coordination of transactions with the subcommittee of the Government Commission for Control of Foreign Investments in the Russian Federation remains of great relevance. The subcommittee has the right to make decisions on the issuance by the Government Commission of permits for residents of the Russian Federation to carry out transactions with foreign persons from unfriendly countries, as well as currency transactions.
We would like to remind you that unfriendly countries, in accordance with the order of the Government of the Russian Federation dated 05.03.2022 No. 430-р, include, among others, Australia, Great Britain, Canada, the Republic of Korea, the USA, Ukraine, Switzerland, Japan and all member states of the European Union.
In particular, in the Decree of the President of the Russian Federation dated 08.09.2022 No. 618 restrictions were established for the execution of transactions that directly and/or indirectly entail the establishment, change or termination of the rights of ownership, use and/or disposal of shares in the authorized capital of limited liability companies or other rights that make it possible to determine the conditions for management of such companies. First of all, these are transactions for disposal of shares in the authorized capital of limited liability companies, which have become relevant due to the desire of a number of Western companies to temporarily or permanently leave the Russian market due to the political situation.
Such transactions can only be carried out on the basis of permits issued by the Government Commission for Control of Foreign Investments in the Russian Federation, which, if necessary, contain the conditions for carrying out these transactions. The procedure and criteria for issuing permits are constantly updated with a tendency to become stricter, which is aimed at complicating the exit of Western businesses from the Russian market and maintaining their presence in the Russian Federation.
In addition to the requirements for documents that must be drawn up and submitted for approval, from the end of 2022, in order to alienate the share of an “unfriendly” participant of a limited liability company, it is necessary to pay a voluntary contribution to the budget of the Russian Federation (see our previous review on changes in this area), as well as to carry out the transaction with a mandatory discount.
At the end of October 2024, the Ministry of Finance of Russia published an updated regulation (Extract from the minutes of the meeting of the subcommittee of the Government Commission for Control of Foreign Investments in the Russian Federation dated 15.10.2024 No. 268/1). The new procedure includes the following:
- The amount of the voluntary contribution to be paid to the budget when Russian companies are disposed of by “unfriendly” participants has increased. Now it is 35% of the market value of the asset based on the results of its independent assessment (previously it was necessary to pay 15%).
An installment plan was introduced for payment of the contribution. 25% of the asset value must now be transferred to the Russian Federation budget within a month from the date of the transaction, 5% within a year, and another 5% within two years from that date. - In addition, the size of the mandatory discount to the market value of the asset upon alienation of an LLC has been changed. Now it must be a minimum of 60%, whereas previously the company could be sold for 50% of its market value.
Also, if the market value of the alienated assets is more than 50 billion rubles, the consent of the President of the Russian Federation will be required to complete the transaction.
The new conditions should apply both to future applications for approval of transactions, and to those already submitted, but not considered by the Government Commission.
Other news includes amendments to the Decree of the President of the Russian Federation dated 04.05.2022 No. 254 regarding the payment of profit of Russian resident companies to their foreign participants.
Let us remind you that in order to pay “unfriendly” participants profit in an amount exceeding 10 million rubles per calendar month or the equivalent of this amount in foreign currency, it is necessary to follow the procedure established by the Decree of the President of the Russian Federation dated 05.03.2022 No. 95. This procedure involves opening a special account of type “C” in a Russian credit institution in the name of a foreign creditor, through which the corresponding settlements are made. At the same time, the Ministry of Finance of the Russian Federation was given the authority to determine a different procedure for payment of residents’ profits to foreign creditors, which meant the need to obtain permissions from the Ministry of Finance for this procedure.
From 09.09.2024, the authority to issue permits for the payment of dividends by Russian companies to persons from unfriendly countries was granted to the Government Commission for Control of Foreign Investments in the Russian Federation. Such permits may contain conditions for the payment of profits.
The Government of the Russian Federation will additionally develop and approve the procedure for issuing such permits by the Government Commission. After the adoption of the changes, the procedure and terms for approving the payment of dividends may become milder.
We will keep you updated on the news of the relevant regulation, and are also ready to provide legal support when interacting with authorized bodies on issues of approving transactions and paying dividends to “unfriendly” foreign persons.
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Federal accounting standard FSBU 4/2023 “accounting (financial) statements
The new Federal Accounting Standard FSBU 4/2023 “Accounting (Financial) Statements” is mandatory for use starting with the accounting statements for 2025 in all commercial organizations in the real sector.
The standard regulates the composition and content of information, the composition of appendices to the balance sheet and the statement of financial results, the composition of appendices to the balance sheet and the statement on the proper use of funds, the composition of interim financial statements, sample forms of financial statements and the conditions for the reliability of financial statements.
The composition of the annual and interim financial statements in accordance with the cl. 5 and 6 of FSBU 4/2023 of a commercial organization includes a balance sheet, a statement of financial results and appendices thereto. The appendices to the balance sheet and the statement of financial results consist of a statement of changes in equity, a statement of cash flows, and notes to the balance sheet and the statement of financial results.
Balance sheet
An idea of the financial position of an economic entity as of the reporting date is provided by the disclosure in the balance sheet of at least the following indicators: intangible assets; fixed assets; investment property; deferred tax assets; financial investments; inventory; long-term assets for sale; value-added tax on acquired assets; accounts receivable; cash and cash equivalents; equity (for commercial organizations)/targeted financing (for non-profit organizations); borrowed funds; accounts payable; deferred tax liabilities; provisions (cl. 9 of the FSBU 4/2023).
In addition to the indicators given in the cl. 9 of the Standard, other indicators may be disclosed considering materiality (for example, indicators of goodwill; intangible exploration assets; tangible exploration assets; capital investments in intangible asset objects; capital investments in non-current assets; rights to use the assets investment in a lease; underbillings; lease liabilities (cl. 10 of the FSBU 4/2023).
Statement of financial results
The statement of financial results should give an idea of the financial results of the activities of an economic entity for the reporting period. The statement of financial results discloses information about all income and expenses of an economic entity (cl. 25 of the FSBU 4/2023).
One of the main changes in the statement of financial results is the indicator of profit (loss) from discontinued operations (less the related corporate income tax). It is disclosed separately from profit (loss) from continuing operations before taxation.
Cl. 28 of FSBU 4/2023 determines the procedure for offset between indicators of other income and other expenses. An offset between these indicators is made if they are related to one (for example, the result from the disposal of non-current assets, the result from the disposal of a capital investment object) or several similar facts of economic life (in particular, exchange rate differences, the result of revaluation of non-current assets included in the income or expenses of the reporting period, the result of impairment of non-current assets and recovery of impairment included in the expenses or income of the reporting period). An exception is when the separate presentation of such income and expenses can affect the decisions of users of financial statements or such presentation is provided for by other standards.
Clause 29 of FSBU 4/2023 contains a list of income and (or) expenses that, taking into account materiality, are disclosed in the statement of financial results or notes. This list includes indicators of income and (or) expenses for the reporting period related to the impairment of inventories and reversal of impairment, impairment of non-current assets and reversal of impairment, revaluation and disposal of non-current assets, settlement of litigation and write-off of provisions.
According to the cl. 30 of FSBU 4/2023, the notes disclose information on the composition of expenses for ordinary activities recognized in the statement of financial results (taking into account changes in the balances of work in progress and finished goods). The information is presented in the context of the relevant elements.
Statement of changes in equity
The sample report presents the result of changes in equity for the reporting period, and not separately the increase and decrease in capital, as in the form.
All changes are reflected in one table, including information on the impact on each component of equity of adjustments to the reflection of the consequences of changes in accounting policies and the correction of significant errors in accounting.
The accumulated revaluation of non-current assets is allocated as an independent component of capital.
Statement of cash flows
In the sample report, a separate line singles out cash flow receipts from current operations in the form of interest on accounts receivable from customers. Apart from that, the composition of the information in the sample corresponds to the composition of the information in the form of the cash flow statement, approved by the Order of the Ministry of Finance of Russia dated 02.07.2010 No. 66n.
Notes
The notes disclose information that is necessary for users of financial statements to make economic decisions, but is not disclosed in the balance sheet, statement of financial results, statement on the planned use of funds, statement of changes in equity, or statement of cash flows (cl. 40 of the FSBU 4/2023).
Cl. 46 of FSBU 4/2023 specifies the list of information disclosed in the Notes.
We will be happy to answer your questions regarding FSBU 4/2023.
Contacts:
Eugenia Chernova
Olga Kireyeva
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Changes in corporate legislation from 01.09.2024
We hereby inform you that Federal Law No. 287-FZ of August 08, 2024 introduced a number of important changes affecting both limited liability companies (OOO) and joint-stock companies (AO). The changes come into effect at different times. In this message, we would like to talk about changes in relation to OOO that will be in effect from September 01, 2024.
From this date, the resolution on the election (appointment) of the sole executive body of the OOO – for example, the general director – will need to be necessarily certified by a notary. Also, when registering such changes in the Unified State Register of Legal Entities, a notary will be the applicant.
Thus, the procedure for changing the general director in an OOO has been significantly changed. Previously, participants could make such a resolution without a notary (if an alternative procedure was stipulated in the articles of association), and then the new director would sign the application for registration himself. Now the participants or their representatives will be required to be present at the Russian notary to make a resolution (with the issuance of the appropriate certificate), after which the notary will sign an application sent by him to the registration authority.
For foreign participants in Russian OOO, such changes mean the presence of two options:
- arrival in the Russian Federation and visiting a Russian notary to make a resolution on changing the director of a controlled Russian company;
- issuance of a power of attorney to Russian representatives for carrying out such actions (please note that the power of attorney must be properly legalized and translated into Russian).
At the moment, we are awaiting clarification regarding whether notarization will be mandatory for participants to make resolutions on extending the powers of the general directors of OOO, as well as the beginning of the liquidation of controlled companies.
With regard to the liquidation of an OOO, from September 01, it is legislatively confirmed that the notary submits to the Federal Tax Service (FTS) a notification about the formation of a liquidation commission/appointment of a liquidator. Such a notification is usually sent simultaneously with the message that the legal entity is entering into the process of liquidation. The notification shall be submitted to the Federal Tax Service by the notary who certified the liquidator’s signature on it, no later than the end of the working day on which the notification was signed.
According to another change, from September 01, the list of information on shares in the authorized capital of OOO, which is contained in the Unified State Register of Legal Entities, is being expanded. The Register will contain information about the arrest of the share imposed by the court or enforcement officer. So far, the Unified State Register of Legal Entities includes information on the size, nominal value of shares and shareholders.
In the future, we will inform you about other significant changes to corporate legislation introduced by Federal Law No. 287-FZ dated August 08, 2024.
We will be happy to answer your questions and, if necessary, support you in the preparation, signing and submission of relevant documents to the authorized bodies.
Contacts:
Maria Matrossowa
Nadezhda Maskaeva
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Counterparty verification in CIS countries: Kazakhstan
We would like to draw your attention to the screening possibilities of foreign counterparties in the Republic of Kazakhstan.
To reduce risks and check the reliability, solvency and security of your foreign counterparty, you should take the following steps:
- Legal check;
- Financial check;
- Check valid licences, if applicable;
- Check other factors such as publicly available information / business reputation: customer reviews, relationships with partners or contractors.
As part of the legal review of an LLP (Limited Liability Partnership or “TOO”), which acts as a separate legal entity based on its own Charter, you should request the following legal documents:
- Charter;
- Memorandum of Association (however, the counterparty may refuse to provide this as the provisions may be confidential);
- Resolution/protocol on the appointment of the directors;
- State registration certificate – certificate of registration. What to check: Consistency of the information in the certificate with other incorporation documents;
- Business Identification Number (BIN) – a unique number created for a legal entity (branch and representative office) and self-employed persons;
- Registration number of the VAT payer’s certificate.
Also pay attention to the company’s legal address for local authorities. It must be specified in the Charter and other documents when registering the LLP and can be either a commercial premises or a private address (e.g. the founder’s flat).
There are following risk factors:
- “mass registration address”;
- mismatch between the legal and actual addresses (when submitting to the tax office), which is especially relevant for VAT payer counterparties.
The charter capital of an LLP must be at least 100 times the monthly calculate on index (MCI) at the time of submitting the formation documents for state registration. Fr om January 1, 2024, the MCI will be 3,692 tenge, i.e. the minimum capital must be 369,700 tenge (approx. RUB 73,000). The charter capital must be fully paid within one year from the date of registration. For small companies (up to 100 employees, income up to 300,000 MCI/year) there is no minimum capital (it can therefore be 0 tenge).
The executive body can be collective (directorate) or individual (director). An LLP can have several directors who act independently of each other (but only natural persons).
In addition, we would like to draw your attention to the official regime of “suspension of activity” in the Republic of Kazakhstan (the official analogue of “sleep mode” in the Russian Federation). During suspension, a company cannot conduct any profitable activities, but it is not liquidated and can be reinstated. Information on companies whose activities have been suspended can be obtained from the website of the State Revenue Committee of the Ministry of Finance of the Republic of Kazakhstan (SRC).
Further, in case the signatory of the contract is a director acting on the basis of the Charter, you should check the following aspects:
- Timeliness of the authorization (the data in the decision / protocol of appointment should coincide with the data in the state registers);
- Duration of the authorization;
- Existence of possible restrictions (e.g. transactions above a certain amount may require the approval of the participants, this may be specified in the Charter);
- Delimitation of powers if there are several directors.
If the signatory of the contract is acting on the basis of a power of attorney, be sure to request and scrutinize it for:
- The authority of the person issuing the power of attorney. If it is not signed by a director, but by another person based on the power of attorney with the right of overriding power of attorney, you should also request and check the original power of attorney;
- Description of the powers of the person acting on the basis of the power of attorney.
Wh ere to get data (open sources):
- Portal of the Bureau of National Statistics of the Agency for Strategic Planning and Reforms of the Republic Kazakhstan (RK).
Here you can find basic information about the company.
- Portal of the State Revenue Committee of the Ministry of Finance of the RK (www.kgd.gov.kz).
Here you can find:
- Details on suspension / non-suspension of activities;
- Information on the absence (presence) of tax arrears;
- Total amount of taxes paid;
- Presence of the counterparty in the List of unreliable taxpayers;
- Information about being / not being in the process of liquidation.
Here you can find the availability of open and past court cases.
- Public procurement portal.
Here you can see if the counterparty is on the list of unfair participants in public procurement.
- Portal of the Electronic Government of the Republic of Kazakhstan Egov.kz.
Here you can find:
- Information about the registered legal entity as of a given date;
- Details of the latest amendments to the constituent documents;
- Information about participation of the legal entity in other legal entities;
- Information on the presence of branches and representative offices of the legal entity;
- Information on the category of the subject of entrepreneurship;
- Data on encumbrances (seizure) on the legal entity’s share;
- Information on recognition of the legal entity as an inactive legal entity or involvement of its participants in inactive legal entities.
Unfortunately, as in many other jurisdictions, to obtain full data from public official sources, in most cases verification or authorization may be required, which requires a local phone number or IIN / BIN (analogue to the Russian TIN). In this regard, it may be necessary to engage a local partner to carry out a full-fledged verification.
For bigger or more significant deals, of course, the financial condition of the counterparty should be checked. For this purpose, it is necessary to request and analyze financial and tax statements for the last reporting periods:
- Balance sheet,
- Profit and Loss Statement,
- Cash flow statement.
Analyzing the financial statements will help to understand how successful and sustainable the company is, and to identify problems / risk factors.
We would also advise you to look at:
- review of financial ratios,
- analysis of current assets and total debt,
- profit and loss analysis,
- and get information about the bank details of the counterparty in advance – not all banks in Kazakhstan accept and send payments to Russia or do so with restrictions on the type of currency / banks from the Russian Federation.
We will be happy to answer your questions and, if necessary, carry out a counterparty check at your request.
Contacts:
Maria Matrossowa
Nadezhda Maskaeva
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Review article “International payment practices in the current environment”
Exclusively for the Russian Business Guide magazine, Daria Pogodina, Managing Director of swilar presented a review article “International payment practices in the current environment”.
You can read the article online in Russian or English, or download two-language article in pdf-format by clicking the “Download en” button below the message.
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
New in the rules for issuing permits by the government commission
We bring to your attention a review of the latest changes in the procedure for transactions with shares of OOOs with participants from unfriendly countries.
We would like to remind you that any transactions or groups of transactions with securities of Russian legal entities and/or shares constituting the share capital of Russian legal entities require obtaining permits from the Government Commission and performing a number of procedures (obtaining an independent assessment, establishing KPIs, etc.).
On 23.01.2024, Decree of the Government of the Russian Federation dated 22.01.2024 No. 40 “On amendments to the Decree of the Government of the Russian Federation dated 06.03.2022 No. 295” (hereinafter – the “Decree No. 40”) was published, which contains some clarifications of the procedure.
Decree No. 40 established the need to comply with certain previously formulated conditions for obtaining permits (see Extract from the decision of the subcommission dated 07.07.2023 No. 171/5) and made some additions.
In particular, it is now established at the regulatory level (clause 5 (1) of the Rules approved by the Decree of the Government of the Russian Federation dated 06.03.2022 No. 295, hereinafter – the “Rules”) that the following information must be additionally included in the application for a permit:
- report on an independent assessment of the market value of the relevant securities of Russian legal entities and/or shares constituting the share capital of Russian legal entities.
This assessment must be carried out by an appraiser engaged in private practice and included in the list of appraisers (appraisal organizations) recommended by the subcommission to carry out such an assessment, or by an appraiser who has entered into an employment contract with a legal entity included in such a list (paragraph 3 of clause 1 of Decree No. 40). The right to determine the specified list is granted to the subcommission (clause 8 of Decree No. 40).
- key performance indicators and their target values for buyers, proposed as conditions for the implementation of transactions or a group of transactions.
Decree No. 40 also details the procedure for monitoring the achievement of key performance indicators.
In particular, Decree No. 40 clarifies who will monitor the implementation of the set KPIs (performance indicators). Monitoring of achievement of indicators and their target values will be carried out by:
- federal executive authorities (in each case, the authority will be determined depending on the scope of activity of the legal entity or party to the transaction), and (or)
- the Central Bank of the Russian Federation,
on the basis of documents confirming the achievement of these indicators and their target values, submitted within the time limits established in the decisions of the subcommission (clause 8 of Decree No. 40).
Please note that, in accordance with the clause 5 (2) of the Rules, the requirement to include additional information in the application in the form of an independent assessment report, as well as KPIs, does not apply to transactions and operations:
- between persons included in the same group of persons in accordance with competition law,
- between persons associated with unfriendly countries.
Additionally, you can read our previously published reviews on the topic: on the procedure for issuing permits for transactions with shares in the share capital of OOOs, on the conditions for obtaining permits for transactions with shares in OOOs, as well as on changes to these conditions.
We will be happy to answer your questions!
Contacts:
Maria Matrossowa
Yulia Belokon
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Submission of information about members of a foreign organization
Please note that all representative offices and branches of foreign companies are required to submit information about the members and beneficiaries of their parent structures to the tax authority by 28.03.2024.
According to the clause 3.2 of the article 23 of the Tax Code of the Russian Federatio , foreign organizations (FO), as well as foreign structures without formation of a legal entity (FSWFLE), are obliged annually no later than March 28:
- to submit information about the members of such a FO (for FSWFLE – information about its founders, beneficiaries and managers) as of December 31 of the year preceding the year of submission of the specified information to the tax authority at the place of their registration, as well as
- to disclose the procedure for indirect participation (if any) of an individual or public company in the event that the share of their direct and/or indirect participation in the FO (FSWFLE) exceeds 5%.
This obligation does not apply to foreign companies that are registered with the Russian tax authorities only because of the provision of services in electronic form, as well as to subsidiaries (OOO) with foreign participation.
The form of communication about the members of a FO (for a FSWFLE – about its founders, beneficiaries and managers), the format of its submission in electronic form, as well as the procedure for filling in the form are approved by the Order of the Federal Tax Service of Russia dated 01.12.2021 No. ED-7-13/1046@.
Wrongful failure to submit (untimely submission) by a foreign organization (foreign structure without formation of a legal entity) of the above information to the tax authority entails a fine of 50,000 RUB (clause 2.1 of the article 129.1 of the Tax Code of the Russian Federatio ).
You can find information previously published by us on this topic here.
We will be happy to answer your questions and offer our assistance in creating the report.
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.