


Category: Taxes
Legislative and Enforcement Practice Digest: September 2026
Dear Colleagues,
Updating the information previously provided, we present a fresh overview of recent legislative developments and enforcement practice covering September 2026, as well as changes expected in the coming months.
1. Payments
1.1. New restrictions on taking cash rubles abroad
On 29 September 2026, the President of the Russian Federation signed Decree No. 706, amending Decree No. 193 of 25 March 2026 on the special procedure for taking Russian cash currency abroad. The decree entered into force on the date of signature (see also media reports 1, 2).
Key changes:
- For individuals, the limit on taking cash rubles to EAEU member states has been reduced from the equivalent of USD 100,000 to RUB 1 million; any excess is subject to seizure. Larger amounts may still be taken out only through international airports designated by the Russian Government, with bank documents confirming withdrawal of the funds from an account;
- The restrictions have been extended to Azerbaijan, Tajikistan and Uzbekistan;
- For legal entities and individual entrepreneurs, the ban in force since 1 April 2026 on taking cash rubles to these countries remains in place regardless of the amount; a violation entails seizure of the entire amount. Exceptions apply to international transport where both the point of departure and destination are outside Russia, subject to supporting documents, and to transfers based on notification by the Russian Ministry of Foreign Affairs to support diplomatic missions and consular posts.
The Russian Government, in agreement with the Bank of Russia, has been instructed to approve a procedure for recording cash rubles taken abroad within three months.
The following previously introduced restrictions also remain in force:
- Since 2 March 2022, taking foreign cash currency exceeding the equivalent of USD 10,000 out of Russia has been prohibited;
- The Bank of Russia has extended restrictions on foreign cash withdrawals until 9 March 2027: individuals may withdraw no more than USD 10,000, or the equivalent in euros, from foreign-currency accounts opened before 9 March 2022; residents may receive cash US dollars, euros, pounds sterling and yen only for business travel expenses within the prescribed limits; non-residents may not receive cash in these currencies.
1.2. Non-resident transfers: restrictions retained
The Bank of Russia has retained for six months from 1 October 2026 the ban on transfers abroad from accounts held with Russian brokers and trust managers by non-resident individuals and legal entities from unfriendly states. Funds of foreign investors recorded in type “In” accounts remain exempt.
As a reminder, the Bank of Russia’s general restrictions on cross-border transfers by non-residents from unfriendly countries are currently in place through 7 December 2026 inclusive.
Individuals resident in unfriendly countries who are officially employed in Russia may transfer funds abroad up to the amount of their salary. The ban on transferring funds abroad remains in place for legal entities from unfriendly states; it does not apply to foreign companies controlled by Russian persons.
No decision has yet been taken on the arrangements to apply after 7 December.
1.3. New channels: cryptocurrency settlements in foreign trade
As previously reported, Federal Law No. 282-FZ “On Digital Currencies and Digital Rights” entered into force on 1 September 2026, allowing digital currency to be used for settlements under foreign trade contracts (see our previous overview and our 2024 article on the legalization of cryptocurrencies).
On the same day, according to media reports, Sberbank launched a cross-border cryptocurrency settlement service for corporate clients engaged in foreign trade. Public sources indicate an average transaction cost of 0.3%, no minimum payment amount, transfers between crypto wallets completed within minutes, and automatic generation of documents for currency control purposes (see report).
Legislation on the taxation of cryptocurrency transactions is still being developed. Before using the new channel, we recommend agreeing with your bank on the supporting documents required and reviewing the accounting and tax treatment of such settlements.
1.4. Bank of Russia plans for cross-border settlements
On 11 September 2026, the Bank of Russia published the draft Guidelines for the Development of the Financial Market for 2027–2029.
For foreign trade settlements, the regulator plans to develop alternative settlement mechanisms and payment channels, reduce business costs and gradually lift restrictions on capital movements as the economy adapts.
In addition, according to media reports, the Bank of Russia plans to increase the limit on transfers between legal entities through the Faster Payments System. The timing and specific parameters have not yet been determined; we will monitor developments.
1.5. Digital ruble: the first stage of mass implementation has begun
From 1 September 2026, systemically important banks and banks significant in the payment services market must enable clients to transact in digital rubles. Merchants with revenue exceeding RUB 120 million in the previous year that are serviced by such banks must accept digital ruble payments (see Bank of Russia information). Further stages are scheduled for 1 September 2027 and 1 September 2028.
2. Banking news
2.1. Tax registration through a bank for foreign organizations
From 1 September 2026, under Federal Law No. 416-FZ of 17 November 2025, a foreign organization opening an account with a Russian bank is registered with the tax authority on the basis of the bank’s application. Within five days of receiving that application, the tax authority registers the organization and sends the bank an extract from the Unified State Register of Taxpayers. The foreign company no longer needs to apply to the tax authority itself.
For more on opening and servicing accounts for foreign companies, their Russian subsidiaries and representative offices, see our overview.
See also our overview of the legal forms through which foreign businesses can operate in Russia.
2.2. More banks subject to sanctions
On 23 July 2026, the Council of the EU adopted the 21st sanctions package. In the financial sector:
- The transaction ban was extended to a further 33 Russian credit and financial institutions;
- A bank in Kyrgyzstan connected to the Financial Messaging System (SPFS), as well as three other banks in third countries facilitating sanctions circumvention, became subject to the ban;
- Transactions were prohibited with 14 cryptocurrency platforms registered in Georgia, Panama, the UAE, the Marshall Islands, Kyrgyzstan and Belarus;
- Courts and competent authorities in EU member states were granted the right to refuse recognition and enforcement of judgments arising from claims brought before Russian courts.
On 6 August 2026, the United Kingdom added six Russian banks to its sanctions list: Ozon Bank, Roseximbank, Center-invest Bank, Realist Bank, Stavr Bank and Teleport Bank.
On 18 September 2026, H.R. 5334, the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026, was signed into law in the United States, expanding the statutory basis for sanctions, tariff measures and prohibitions concerning Russia. The practical consequences will depend on the US administration’s implementation decisions. We will monitor developments.
Before making cross-border payments, we recommend checking the current status not only of the payer’s and recipient’s banks but also of correspondent banks.
3. Supply chains
3.1. SPOT: security payments on supplies from Belarus from 1 November
As previously reported (see our previous overview), the System for Confirmation of Expected Goods (SPOT) has operated since 1 June 2026, and security payments have been mandatory for supplies from Armenia, Kazakhstan and Kyrgyzstan since 1 July.
The exemption from security payments for supplies from Belarus entering via the Russia–Belarus border applies through 31 October 2026 inclusive; no information on an extension was available when this overview was prepared.
Accordingly, from 1 November 2026, obtaining a QR code for goods imported from Belarus by road will require a security payment equal to the import VAT and excise duties.
According to information from the Ministry of Finance and the Federal Customs Service, additional budget receipts generated by the system had reached RUB 33.8 billion by 10 September 2026, against an annual target of RUB 50 billion.
The business community’s proposal to replace the security payment with a bank guarantee is to be considered in the autumn. Businesses also propose reducing the revenue threshold for exempting compliant taxpayers from RUB 30 billion to RUB 5–10 billion.
Final decisions on adjustments to the system have not yet been taken.
3.2. Customs monitoring: pilot extended until 2029
Russian Government Resolution No. 1188 of 18 September 2026 extends the customs monitoring pilot until 31 March 2029, previously 31 March 2027. Eligibility has also been expanded: Russian declarants not classified as high-risk may join. Applications will be accepted until 30 September 2028. The resolution enters into force on 19 October 2026.
As a reminder, participants provide customs authorities with remote access to data in their accounting systems and, where risks are identified, have an opportunity to rectify violations themselves before customs control measures are applied.
3.3. Electronic transport documents: no penalties before March 2027
From 1 September 2026, under Federal Law No. 140-FZ, carriers, freight forwarders, consignors and consignees are required to issue transport documents electronically through the State Information System for Electronic Transport Documents (GIS EPD). The requirement covers road, rail and air consignment notes, transport orders and freight forwarding documents.
Paper documents remain available, in particular:
- For military and special cargo transport;
- For transactions with foreign counterparties;
- For transport for individuals’ personal needs;
- For border-area operations and in territories with special status.
According to information from the Ministry of Transport, an adaptation period applies until 1 March 2027: penalties for using paper documents instead of electronic ones will not be imposed. Please note that the ministry announced this adaptation period, but no regulatory act on the matter had been published when this overview was prepared.
3.4. New obligations for manufacturers and importers
A technology levy introduced by amendments to the Federal Law “On Industrial Policy in the Russian Federation” will apply from 1 December 2026. Manufacturers and importers of radio-electronic products will pay the levy.
The Ministry of Industry and Trade has prepared a draft order setting rates, including RUB 746 per laptop and RUB 373 per smartphone; rates are lower for products included in the relevant directory and higher for those not included (see also media coverage). The rates remain at the draft stage.
In addition, from 1 October 2026, manufacturers begin applying identification markings to household and sanitary-hygiene products, including paper towels, toilet paper, toothbrushes and diapers. Registration in the Chestny ZNAK system has been mandatory since 1 September 2026 (Russian Government Resolution No. 656 of 30 May 2026).
4. Other developments
4.1. Taxation
4.1.1. Under discussion: 35% tax on dividends paid into type “C” accounts?
On 24 September 2026, the Russian Government approved the budget package for 2027–2029; the bills are scheduled to be submitted to the State Duma by 1 October. The proposed tax measures are intended to take effect from 2027 (see media reports 1, 2). They include:
- An increase from 15% to 35% in the corporate income tax rate on dividends paid into type “C” accounts to non-residents from unfriendly states;
- Taxation of individuals’ passive income, including dividends, deposit interest, securities transactions and property sales, at progressive rates of 13–22%; income from deposits of up to RUB 1 million would not be taxed;
- VAT at 22% on cross-border e-commerce, with electronic platforms acting as tax agents, and a customs fee of RUB 100 per parcel valued at up to EUR 200;
- Corporate income tax at 15% on passive income of mutual investment funds;
- A tax on additional income arising from increases in world prices for companies extracting solid minerals, at 30%, or 20% for gold producers.
The higher dividend tax rate would affect foreign groups receiving dividends from Russian subsidiaries. As a reminder, the double taxation treaty between Russia and Germany will also be suspended from 1 January 2027 (see our overview and Telegram post).
We recommend taking the proposed changes into account when planning the timing of profit distributions. The parameters may change as the bills are considered; we will monitor developments.
4.1.2. Official: new rules on tax penalties
From 1 September 2026, amendments to Articles 112 and 114 of the Russian Tax Code introduced by Federal Law No. 425-FZ of 28 November 2025 apply: where mitigating circumstances exist, a penalty is reduced by a factor of at least two but no more than ten; previously, there was no upper limit on the reduction (the amendments were introduced by Article 1 of Federal Law No. 425-FZ; see the current version of Article 114 of the Tax Code).
As a reminder, Bill No. 1215257-8 on easing liability for late submission of returns, which we previously reported, has been enacted as Federal Law No. 201-FZ of 26 June 2026:
- The penalty under Article 119(1) of the Tax Code does not apply if a late tax return or calculation shows no tax payable;
- Individuals are not fined for failing to submit a 3-NDFL return upon the sale or gift of real estate;
- Taxpayers may submit evidence of mitigating circumstances together with the late return.
4.1.3. Consideration of tax audit materials by videoconference
From 1 September 2026, Federal Law No. 425-FZ (Article 1; see the current versions of Article 101 and Article 101.4 of the Tax Code) amended Article 101(2) and Article 101.4(7) of the Tax Code to permit participation by videoconference in the consideration of tax audit materials and reports on tax offenses identified outside an audit.
The procedure for such participation was approved by Federal Tax Service Order No. ED-1-2/567@ of 11 August 2026, published on 31 August 2026 and entering into force one month after publication:
- Participants connect from the tax office at the organization’s location or the individual’s place of residence, provided the tax authorities have the technical capability;
- A request to participate by videoconference must be sent to the tax authority considering the materials;
- The tax authority must notify the applicant of the possibility of videoconference participation at least three working days before the hearing;
- In the event of technical failures, consideration is postponed or conducted in person; videoconferencing is not used where the materials contain state secrets.
At the same time, Federal Tax Service Order No. ED-1-2/568@ of 11 August 2026 approved the format and procedure for submitting written objections and supporting documents electronically.
4.1.4. Tax monitoring: new rules for reorganizations
Amendments to the tax monitoring procedure introduced by the same Law No. 425-FZ took effect on 1 September 2026 (Article 1; see the current version of Article 105.26 and the subsequent articles of Section V.2 of the Tax Code):
- Legal successors of reorganized participants may continue tax monitoring without meeting the monetary thresholds if they update the previously submitted documents within one month; the monitoring period is not interrupted by the reorganization;
- The grounds for early termination of monitoring have been expanded, including non-compliance with requirements for information exchange, information systems and internal control systems, and repeated violations of information access procedures.
As a reminder, our previous overview covered the government-approved bill on mandatory tax monitoring for special economic zone residents (see also our Telegram post). The general tax monitoring procedure is described in our overview.
4.1.5. Accounting: amendments to PBU 18/02
Russian Ministry of Finance Order No. 121n of 20 August 2026 amended PBU 18/02 “Accounting for Corporate Income Tax.” The amendments concern accounting for deferred tax assets and liabilities when corporate income tax rates change, and the recognition of income tax relating to transactions included in the period’s comprehensive financial result.
The order entered into force on 29 September 2026. We recommend assessing its impact on the 2026 annual financial statements in advance.
4.2. Corporate law and transactions with unfriendly persons
4.2.1. Temporary management in the event of security violations
Presidential Decree No. 604 of 24 August 2026 “On Measures to Ensure the Security of Critical Infrastructure Facilities of the Russian Federation” empowers the Russian Government, acting on instructions from the President, to introduce temporary management of business entities’ property where critical infrastructure security requirements are violated. The facilities concerned include fuel and energy, industry, communications, transport and logistics, municipal infrastructure and life-support facilities.
Grounds may include, in particular:
- Failure to take security measures, or delays in taking them;
- Ineffective organization of measures to counter unmanned aerial vehicles;
- Delays in restoring a facility’s operation.
Rosimushchestvo is appointed temporary manager unless the Government designates another person. The temporary manager may not dispose of the property. Unlike Decree No. 302, the new mechanism is not limited to assets of persons from unfriendly states.
4.2.2. Bill on creditor protection during reorganization
The Russian Government has submitted Bill No. 1342008-8 to the State Duma to amend Article 60 of the Civil Code. It proposes that a court should reject a creditor’s demand for early performance due to the debtor’s reorganization if the debtor demonstrates that there is no material threat to performance of the obligation.
If adopted, the amendments could facilitate intragroup reorganizations. The bill is under consideration.
As a reminder, the Russian Ministry of Finance previously clarified when corporate procedures in companies involving persons from unfriendly states do not require Government Commission approval (see our overview).
4.3. Migration
As previously reported, a range of migration law changes takes effect in 2026–2027. The principal changes and our recommendations for employers are set out in our full overview and Telegram posts on digital registration, new personal income tax payments and requirements for highly qualified specialists.
4.3.1. Medical examinations: a uniform 30-day deadline
From 1 September 2026, Federal Law No. 162-FZ of 10 June 2026 (Article 1, amending Article 5 and Articles 6, 6.1, 13 and 13.3 of Federal Law No. 115-FZ “On the Legal Status of Foreign Citizens in the Russian Federation”) establishes a uniform deadline for foreign nationals to undergo medical examinations: 30 calendar days from entry into Russia.
It applies to foreign nationals arriving for more than 90 days or for employment, and when obtaining a work permit, work patent or temporary residence permit. Repeat examinations are conducted annually.
Federal Law No. 163-FZ of 10 June 2026 (Article 1, introducing Article 18.11.1 of the Code of Administrative Offenses) introduced administrative liability for violations of the examination procedure: a fine of RUB 25,000–50,000, with possible administrative expulsion.
4.4. Employment relations
The Russian Government approved the working calendar for 2027 by Resolution No. 1187 of 17 September 2026. Days off are moved from 2 January to 5 November, from 3 January to 31 December, and from 20 February to 22 February. There are 247 working days in 2027; standard working time for a 40-hour week is 1,972 hours.
As a reminder, amendments to the Labor Code took effect on 1 September 2026 under Federal Law No. 144-FZ of 25 May 2026:
- The annual overtime limit may be increased from 120 to 240 hours if a collective agreement or sectoral agreement so provides;
- Overtime exceeding 120 hours is paid at no less than double the regular rate;
- The employee threshold for small businesses permitted to enter into fixed-term employment contracts by mutual agreement has been raised from 35 to 70.
4.5. Personal data: new criteria for “adequate” countries
Federal Law No. 265-FZ of 26 July 2026 was published and entered into force on 3 August 2026, changing the procedure for recognizing foreign states as ensuring adequate protection of personal data subjects’ rights. Participation in Council of Europe Convention No. 108 alone is no longer sufficient: a country’s rules must comply with the Convention and ensure personal data confidentiality and security.
Roskomnadzor approves the list of such states; an updated list had not been approved when this overview was prepared.
A country’s status affects cross-border data transfer procedures, including the use of a parent company’s information systems, cloud services and CRM systems.
We will monitor developments.
4.6. Upcoming deadlines
For planning purposes, we summarize adopted and expected changes taking effect in the coming months:
- 1 October 2026: commencement of marking household and sanitary-hygiene products (section 3.4); the procedure for considering tax audit materials by videoconference takes effect (section 4.1.3);
- 19 October 2026: the resolution extending and expanding customs monitoring takes effect (section 3.2);
- 23 October 2026: Bank of Russia Board meeting on the key rate, currently 14%;
- 1 November 2026: SPOT security payments for supplies from Belarus (section 3.1);
- 1 December 2026: collection of the technology levy begins (section 3.4);
- 7 December 2026: expiry of the current Bank of Russia restrictions on non-resident cross-border transfers (section 1.2);
- 1 January 2027: abolition of separate corporate income tax returns for certain separate subdivisions; suspension of the double taxation treaty with Germany; fixed advance personal income tax payments for foreign workers; an increase in the minimum wage to RUB 28,935, subject to enactment; budget-package tax measures, subject to enactment;
- 1 March 2027: new salary requirements for highly qualified specialists, RUB 717,000 per month (see our overview); end of the adaptation period for electronic transport documents (section 3.3);
- 9 March 2027: expiry of the current restrictions on foreign cash withdrawals (section 1.1);
- 1 September 2027: second stage of digital ruble implementation (section 1.5).
Other news

06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC

28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.

01.09.2026
Company Registration in Russia: Overview of Legal Forms for Foreign Business Presence
A consolidated overview of legal forms available for foreign business presence in Russia, including key registration, tax and reporting requirements relevant for 2026.
Digest of Changes in Legislation and Law Enforcement Practice: July – August 2026
Dear colleagues,
We present a fresh overview of the latest changes in legislation and law enforcement practice covering July – August 2026.
1. Payment Situation
1.1. Bank Deposits of Non-Residents from Unfriendly Countries: Special Procedure and Exceptions
Presidential Decree No. 95 of 05.03.2022 establishes a special permitting procedure for fulfilling obligations to foreign creditors from unfriendly countries if the amount of obligations exceeds 10 million rubles per month (or the equivalent in foreign currency). This procedure involves either obtaining permission from the Government Commission, or crediting funds to special accounts of type “C”.
By the Decree of the President of the Russian Federation dated 01.06.2026 No. 377, the list of obligations subject to Decree No. 95 was expanded. From June 1, 2026, a special procedure was also applied to the obligations of banks to return deposits (deposits) and pay interest on them in favor of foreign creditors from unfriendly countries.
On July 14, 2026, the Bank of Russia published official explanations that clarified the application of Decree No. 377 to bank deposits:
- The threshold of 10 million rubles is applied individually to each depositor (and not in the aggregate for the bank). If the obligations to a specific depositor in a calendar month do not exceed 10 million rubles, the special procedure is not applied.
- If the threshold is exceeded, the obligations are fulfilled by crediting funds to the C-type account; the use of such funds is possible only in authorized areas or on the basis of a special permission of the Government Commission.
- The rules apply exclusively to bank deposit contracts and do not affect bank account or correspondent account contracts.
- In case of early or urgent return of the deposit, as well as when paying interest, a special procedure is applied. At the same time, before the maturity of the obligation, the bank is not obliged to change the status of the deposit (convert it into an account of type "C").
- The decree does not apply to foreign citizens who have a residence permit in the Russian Federation, as well as to Russian companies whose members include persons from unfriendly countries.
Decree of the President of the Russian Federation dated 04.08.2026 No. 550 in Decree No. 95 made additional changes that significantly narrow the scope of the special order in relation to bank deposits. According to the new version, the rules of Decree No. 95 do not apply to obligations on bank deposits (deposits):
- deposited by individuals who are foreign creditors from unfriendly countries;
- introduced by branches, permanent missions and other separate or independent structural subdivisions of organizations – foreign creditors, provided that the place of registration of such subdivisions is the Russian Federation.
In addition, Decree No. 550 grants these individuals, as well as branches, representative offices and subdivisions the right to receive funds in rubles that were credited by credit institutions to accounts of type “C” in the period from June 1, 2026 until the date of entry into force of this Decree (ie until August 4, 2026). Decree No. 550 entered into force on the date of its official publication.
Thus, at present, a special procedure under Decree No. 95 is reserved for bank deposits of non-resident legal entities from unfriendly countries (except for their branches and representative offices registered in the Russian Federation), but does not apply to deposits of non-resident individuals and deposits of Russian subdivisions of foreign organizations. Previously blocked in accounts of type “C” ruble funds of these categories of depositors are subject to issuance.
1.2. Reminder from the Federal Customs Service on the Rules for Exporting Cash Currency
The FCS of Russia reminded that from March 2, 2022, there is a temporary ban on the export of cash foreign currency from Russia in the equivalent of more than $ 10,000. At the same time, the ban does not apply to exported cash in Russian rubles (subject to the rules of customs declaration).
In accordance with the Decree of the President of the Russian Federation dated 25.03.2026 No. 193, the procedure for exporting cash to the EAEU countries has been limited since this year. Now, when exporting cash in the amount of more than $10,000, a written declaration will also be required, and if the amount exceeds $100,000, confirmation of the origin of the funds is required. Filing a declaration does not entail payment of fees.
The explanations of the FCS also describe in detail the procedure for declaring and provide a list of airports that allow the export of cash currency in accordance with the current procedure.
2. Supply Situation
2.1. Clarifications from the Federal Tax Service on the Operation of the SPOT System
In the letter, the Federal Tax Service answered frequent questions of the Eurasian Economic Commission and foreign trade participants about the procedure for the functioning of the national system for confirming the expectation of goods (SPOT), launched from June 1, 2026. Key clarifications:
- Technical support: a round-the-clock support service for the applicant’s service and a Federal Customs Service hotline are organized.
- Security payment is not required for certain categories of goods: return packaging, goods for testing and research, for participation in exhibitions, under lease / leasing agreements, as well as for goods sold to individuals through electronic trading platforms (ETP). For them, a Document on the upcoming delivery (DPPP) is issued without payment.
- The QR code has no expiration date, the route is not specified in the DPPP, the vehicle can be replaced before crossing the border without creating a new DPPP.
- When transiting goods through the territory of the Russian Federation to third countries, registration of DOP and QR code is not required.
- The carrier must have a visualized reference to the QR code and present it at the request of the regulatory authorities.
Recall that the adaptation period (without making security advances) for Armenia, Kazakhstan and Kyrgyzstan operated until June 30, 2026, for Belarus continues to operate until October 31, 2026.
See also in the media.
3. Other Changes
3.1. Taxes
3.1.1. Official: Postponement of the Reduction of the VAT Exemption Threshold under the Simplified Tax System
On July 4, 2026, the President of the Russian Federation signed Federal Law No. 228-FZ, which postpones the reduction of the annual revenue threshold for VAT exemption for business on the simplified taxation system (simplified tax system). As we informed earlier, from January 1, 2026, the threshold was reduced to 20 million rubles, and it was planned to gradually reduce it to 15 million in 2027 and to 10 million in 2028. Now the threshold of 20 million rubles will remain until 2029.
Further reduction of the threshold has been postponed: to 15 million rubles from 2030, to 10 million rubles from 2031.
3.1.2. Discussion: Exclusion of Trade from the Simplified Tax System?
The Ministry of Finance of Russia requested the position of business associations on the issue of excluding wholesale and retail trade from the list of activities for which simplified tax system can be applied (see media 1, 2). The reason was the appeals of the regions about “tax migration” – registration of sellers working through marketplaces in subjects with reduced simplified tax system rates without real activity there.
According to expert estimates, falling budget revenues from such schemes can reach 75 billion rubles in 2026. The business opposes the complete exclusion, offering to focus on suppressing fictitious registration.
A final decision has not yet been made.
3.1.3. Expansion of the Scope of Controlled Transactions: New Low-Tax Jurisdictions
From January 1, 2026, the updated provisions of subitem 3 paragraph 1 of Article 105.14 of the Tax Code of the Russian Federation came into force (introduced by Federal Law No. 425-FZ of 28.11.2025). Now the transaction is recognized as controlled (without interdependence of the parties), if the total turnover with the counterparty exceeds 120 million rubles. per year and the counterparty is registered in a jurisdiction with a profit tax rate of 15% or lower.
This significantly expands the perimeter of control: transactions with independent counterparties from the UAE, Kuwait, Qatar and other Middle East countries fall under it.
There is no official list of such jurisdictions, taxpayers will have to determine rates independently, requesting information from counterparties. Errors in qualifying threaten transfer pricing fines.
It is important to take into account that according to open sources (see media 1, 2), the tax service has intensified inspections of the TP, paying attention not only to intra-group, but also to foreign trade transactions with independent persons from 91 jurisdictions included in the offshore list of the Ministry of Finance, as well as with products from the special list of the Ministry of Industry and Trade (oil, metals, fertilizers, jewelry).
Recall that fines for violations have increased significantly since 2024: for failure to provide notice of controlled transactions – up to 100,000 rubles, for failure to provide documentation for TP – up to 1 million rubles. The Federal Customs Service seeks to resolve most issues at the analytical stage before the on-site inspection.
Our previous detailed reviews on transfer pricing are available via links 1, 2.
3.1.5. VAT in Case of Changes in Tax Rates under Long-Term Contracts
04.08.2026 was adopted Federal law of 04.08.2026 No 293-FZ. The key principle of VAT application: when tax rates change, VAT is not automatically transferred to the buyer. If the buyer cannot accept the tax for deduction, and the parties have not changed the price of the contract, the amount of VAT is calculated based on the value of the contract, invoices are not issued.
3.1.6. Tax Monitoring: Will It Become Mandatory for SEZ Residents?
The government commission approved a bill obliging large and medium-sized residents of special economic zones (SEZs) to switch to tax monitoring within 2 years from the date of conclusion of the agreement (see media 1, 2). For refusal may be provided for termination of the agreement.
See our earlier review on tax monitoring.
3.1.7. Updated Register of Double Taxation Treaties
In July, the Russian Ministry of Finance has traditionally updated the register of agreements on the avoidance of double taxation. As we informed earlier, information on suspension/denunciation has been added to the register.
From January 1, 2027, the Agreement between Russia and Germany of May 29, 1996 (and the Protocol thereto) is fully suspended. Germany notified Russia of this on June 26, 2026. This means the elimination of foreign tax credits, the risk of double taxation and the inability to claim reduced rates at source on dividends, interest and royalties. It should be noted that the German Federal Ministry of Finance uses the term “suspension” rather than “denunciation”, which means temporary non-application.
See more details in our review.
It is also worth mentioning that Spain included the Russian Federation in its national list of “non-cooperative tax jurisdictions” – in terms of the presence in the Russian Federation of special tax regimes for companies with registration in certain administrative regions. The decision comes into force on December 28, 2026. This does not lead to the abolition of the double taxation treaties between Spain and the Russian Federation, but means stricter tax controls, increased verification of the origin of funds and greater attention to transactions related to Russian companies by the Spanish tax and banking authorities. Recall that Russia was included in the “black list” of the EU from January 29, 2026.
3.2. Corporate Law and Transactions with Unfriendly Persons
3.2.1. Reverse Buyback of Assets under Options
04.08. In 2026, the Federal Law No. 319-FZ dated 04.08.2026 was officially adopted, introducing grounds for the judicial termination of the right of foreign investors from unfriendly states to repurchase Russian assets sold after 22.02.2022. For judicial refusal, confirmation of simultaneous fulfillment of the following conditions is required:
- Investor behavior: public support of unfriendly actions, discrediting the Russian Armed Forces, financing of terrorism, a statement on the termination of activities in the Russian Federation, etc.
- Financial parameters: the repurchase price deviates from the market by 25% or more, or the acquirer has made a significant investment in the asset.
The claim can be filed by the acquirer (it is not necessary to wait for the exercise of the option) or the profile FOIV (with the permission of the board). The case will be heard by the Moscow Region Arbitration Court. The investor has the right to demand compensation within a year, while the court can reduce it or refuse it completely.
See more details in our review.
3.2.2. Relaxations for Corporate Procedures
On July 10, 2026, the Ministry of Finance published official explanations from 01.07.2026, which specified the cases when the permission of the Government Commission for transactions with unfriendly persons is not required (under Decree No. 618):
- Amendments to the charter of an LLC related to the formation, definition of competence or termination of powers of management bodies (for example, the creation of a Board of Directors).
- Repayment of the treasury share (change in the size of the participant’s share as a result of repayment of the share owned by the LLC itself, and a decrease in the authorized capital).
See more details in our review.
3.2.3. Review of the Supreme Court of the Russian Federation No. 8/2026: Transactions with Unfriendly Counterparties
On June 22, 2026, the Thematic Review of the Supreme Court of the Russian Federation No. 8/2026 was published, which significantly changes the approach to risk assessment.
Among the key conclusions of the review, the following should be noted:
- Splitting payments (for tranches up to 10 million rubles to circumvent Decree No. 95) is recognized as an abuse of the right (Article 10, 168 of the Civil Code of the Russian Federation) and entails nullity. In the text of the review, the splitting of payments is mentioned in the context of settlements under credit agreements. However, we cannot exclude the risk that the position will be extended to royalties, dividends or other settlements.
- Real estate transactions involving a person under the control of an unfriendly person (participation of more than 50%) are void without the permission of the Executive Committee, even if carried out between the Russian seller and the buyer.
- Assignment of the right of claim (cession) to a friendly person, made in order to bypass accounts of type "C" or "O" is void.
- Settlement agreements that provide for the payment of money not directly to an unfriendly person, but to his representative in circumvention of the permitting procedure, cannot be approved by the court and are void.
- Limitation of liability of banks: the bank is not liable for losses of the client if the transfer was blocked by the intermediary bank in an unfriendly country due to sanctions imposed later, provided that the sender bank is in good faith.
See more details in our review. We also recommend reviewing the full text of the document.
3.2.4. Draft Law on Limiting Subsidiary Liability
The State Duma introduced a bill aimed at a more balanced regulation of the use of subsidiary liability of managers / controlling persons.
Among other things, it is proposed to:
- Apply liability only for intentional actions clearly aimed at causing harm to creditors (management errors and business risk are excluded).
- The possibility of writing off subsidiary liability under a number of conditions (completion of the repeated bankruptcy procedure of a citizen, expiration of 10 years from the date of adoption of the judicial act, good faith behavior).
The bill is under consideration.
In this context, we also recall that in November 2025, the Supreme Court approved a review of the prosecution of controlling persons for the debts of abandoned companies (excluded from the USRLE).
Key findings:
- Controlling persons may be brought to subsidiary liability in case of exclusion of the company from the USRLE, if as a result of their behavior, settlements with creditors of the specified company became impossible;
- The creditor is not obliged to prove the bad faith of the controlling persons, the burden of proof lies on them;
- A lawsuit can be filed even without trying to prevent the company from being excluded from the USRUL;
- The limitation period begins from the moment when the creditor became aware of the exclusion of the company and the controlling person;
- The mere fact of having the status of a sole participant or director does not constitute a basis for liability; it is necessary to prove the real influence and causality.
3.3. Regulation of Cryptocurrencies
11.08.2026 was published almost 300-page Federal law “On digital currencies and digital rights” No. 282-FZ (signed 04.08.2026), establishing the rules for the circulation of cryptocurrencies in Russia. The main provisions come into force from September 1, 2026, the transition period will last until July 1, 2027.
The law introduces 5 categories of regulated organizations (exchanges, brokers, management companies, depositories, exchangers). After July 1, 2027, transactions with cryptocurrency will be possible only through regulated organizations, banks are obliged to refuse other operations. Payment for goods and services with cryptocurrency within the country is prohibited, but it is allowed to use for operations within the framework of foreign trade.
In parallel, laws on the taxation of cryptocurrencies and on liability for illegal transactions are being developed.
See our article on cryptocurrencies in Russian Business Guide magazine here.
3.4. Migration Sphere
A detailed description of the changes is available in our full review.
Below is a brief summary of the main changes:
3.4.1. Digitalization of Registration
- Since June 30, 2026, the Digital Profile of a Foreign Citizen (Decree No. 735) has been formed. It is a single electronic database of documents, employment, education, insurance, offenses and restrictions on entry.
- From July 1, 2026, as part of the experiment (until December 31, 2027), a mobile application “Public Services RuID” was launched to submit an application for entry to the Russian Federation for citizens of visa-free countries (recommended 72 hours before entry). The QR code is valid for 90 days.
- From 01.09.2025 as part of the experiment in Moscow and the Moscow region, the application "Amina" – the official state application for remote migration registration – was put into operation (see also the application information page). With its help, the foreigner submits a notification of the place of stay, and the application automatically transmits to the Ministry of Internal Affairs data on the geolocation of the smartphone. Mandatory registration in the application "Amina" is subject to foreigners from visa-free countries who came to Russia to work.
The experiment started on September 1, 2025 in Moscow and the Moscow region and will last until September 2029 (based on Federal Law No. 121-FZ).
At the same time, from 01.09.2026, Amina will also become mandatory for visa-free foreigners who are in the capital region for more than 90 days for non-working purposes (study, guest visit, long trip to relatives).
- From October 1, 2026 (data transfer) and from January 1, 2027 (full work), an automatic exchange of information between the Federal Tax Service, the Ministry of Internal Affairs and the SFR is introduced.
3.4.2. New Rules on the Subsistence Minimum and Taxes
From 01.01.2027, Federal Law No. 241-FZ and Federal Law No. 242-FZ of 26.07.2026 come into force, which
- Obliges migrant workers to support themselves and their dependents at a level not lower than the regional subsistence minimum. Lack of confirmed income is the basis for revocation of a patent, TRP or residence permit.
- introduces the obligation to pay a new fixed advance payment on personal income tax when working for individuals: 1700 rubles / month, 1200 rubles / month. – under a patent from legal entities, with an increasing coefficient of 50% for each dependent.
3.4.3. Significant Increase in Requirements for Highly Qualified Specialists
26.07. In 2026, Federal Law No. 241-FZ was officially adopted, which increases the basic income requirement for foreign highly qualified specialists by almost 3 times.
The basic minimum wage threshold for maintaining the status of the HQS is increased from 750,000 rubles / quarter (250,000 rubles / month) to 717,000 rubles / month. The new requirements come into force from 01.03. 2027. The reduced threshold (358 500 rubles / month) can be applied for narrow categories (scientific workers, teachers, SEZ residents, accredited IT companies, Skolkovo participants and innovation centers).
In addition, a requirement for annual indexation of the amount of remuneration of the HQS is introduced.
3.4.4. Other Changes
It is important to take into account that from September 1, 2026, new forms of notifications come into force (Order of the Ministry of Internal Affairs of Russia from 12.05.2026 No. 290). At the same time, the notifications will now require a separate consent to the processing of personal data. State duties for legally significant actions in the migration sphere are also significantly increased.
We recommend employers to analyze the situation with HQS, assess the possibility of raising wages to new thresholds and consider alternative options for registration (quota, TRP, residence permit, list of professions).
We have prepared a consolidated overview of the main migration changes and recommendations; the text is available here.
3.5. Identification of Domain Administrators through ESIA
Federal Law No. 569-FZ of December 29, 2025 from September 1, 2026 introduces mandatory identification of domain name administrators in the Russian national domain zones .ru, .rf and .su through the Unified Identification and Authentication System (ESIA) – the portal "Gosuslugi". The requirement applies to all administrators, including foreign nationals and companies. For individuals, a confirmed account on the Gosuslugi is required; for legal entities, registration of the company in the ESIA and the connection of an authorized employee are required.
Without passing the identification, the administrator loses the ability to extend the domain, make changes to the settings or transfer rights. At the same time, the domain will continue to work until the end of the registration period, but after its expiration, it will go to the waiting status, and then it will be released.
We recommend an inventory of all domains in the .ru, .rf and .su zones, check the administrator’s data and, if necessary, urgently update them or change the registrar (if the current one is not integrated with the ESIA).
See also more details in our review.
3.6. Tax Secrecy on Gosuslugi
Since August 1, 2026, the tax secrecy regime has been extended to documents and information from the personal account of the taxpayer on the Gosuslugi portal. Also abolished the obligation of the Federal Tax Service to massively send paper tax notices: now they are sent in electronic form through public services (by default), paper remain only for those who are not registered on the portal.
Other news

06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
01.09.2026
Company Registration in Russia: Overview of Legal Forms for Foreign Business Presence
A consolidated overview of legal forms available for foreign business presence in Russia, including key registration, tax and reporting requirements relevant for 2026.
Overview of changes: Double Taxation Agreement (DTA) and deposits
Dear Colleagues,
This review is related to two recent amendments in financial regulation affecting taxation and banking deposit operations for persons from unfriendly countries
1. Full suspension of the Double Taxation Agreement between Germany and Russia
Since January 1, 2027, the Agreement between the Russian Federation and the Federal Republic of Germany for the Avoidance of Double Taxation regarding to taxes on income and capital dated May 29, 1996, as well as the corresponding Protocol thereto, shall be fully terminated.
Background
The sphere of Double Taxation Agreements (DTAs) has been in a highly turbulent phase in recent years (see, for example, one of our previous reviews on this issue by the link).
The Ministry of Finance regularly updates the register of current DTAs and information on their status on its website. The latest update was published on July 14, 2026.
It should be reminded that Russia unilaterally suspended the application of certain provisions of several Double Taxation Agreements since August 8, 2023 (the Presidential Decree No. 585) – we reviewed this in more detail in the corresponding review.
The suspension affected certain provisions of the Agreement with Germany as well. In particular, the suspension by the Russian Federation covered provisions on the taxation of dividends, interest, royalties, income from real estate and salaries.
At the same time the Agreement itself, as a whole, has formally remained in effect until now.
However, on June 26, 2026, Germany notified the Russian Federation of the full suspension of the Agreement since January 1, 2027.
Key consequences
- Asymmetry of the situation. Germany is fully suspending the Agreement, while the list of norms suspended by Russia formally remains unchanged at the moment.
- Elimination of foreign tax credits. Taxpayers will no longer be able to credit taxes paid in one country against tax liabilities in the other. For individuals (tax residents of Russia) receiving income in Germany, double taxation may arise.
- Impact on business. German subsidiaries with Russian parent structures will no longer be able to benefit from reduced withholding tax rates on dividends, interest and royalties under the Agreement. The importance of proper transfer pricing documentation increases, as tax authorities will pay more attention to cross-border transactions.
Therefore, it should be reminded that since January 1, 2024 new stricter regulations have taken effect in Germany due to inclusion of Russia in the EU "blacklist" for tax purposes and the application of the German Tax Haven Defense Act (Steueroasen-Abwehrgesetz).
Accordingly, the full suspension of the DTA since 2027 further tightens and reinforces this situation. However, the German Federal Ministry of Finance uses the term "suspension" rather than "denunciation" in accordance with the Article 29 of the DTA. This means that the agreement is not formally terminated, but is merely temporarily not being applied.
2. Clarification of the procedure for bank deposits operations of foreign persons
The Presidential Decree No. 377 dated June 1, 2026, has expanded the list of obligations subject to the special procedure established by the Decree No. 95. It should be reminded that this refers to the mandatory permitting procedure for certain categories of payments (such as dividends, loans) where the amount exceeds the limit of 10 million rubles (or equivalent in foreign currency) per month. The specified payments require either permission from the Government Commission or should be made through the special type "C" accounts.
Since June 1, 2026, this procedure also applies to obligations of banks to repay deposits and pay interest to foreign creditors from unfriendly countries.
Key changes:
- Extension of the special procedure to bank deposits. Previously the Decree No. 95 regulated the procedure for fulfilling obligations to certain foreign creditors. As of June 1, 2026, obligations under bank deposits have been included in this list.
- Who is subject to this law: foreign companies from unfriendly countries (and structures controlled by them, with the exception of Russian legal entities), their branches and representative offices in the Russian Federation, as well as individuals who are the citizens of unfriendly countries.
- Who is not subject to this law: foreign citizens with a residence permit in Russia, as well as Russian companies whose participants/shareholders include persons from unfriendly countries.
On July 14, 2026, the Bank of Russia issued official clarifications that specify the implications of the Decree No. 377 for depositors. In particular, it was specified that:
- The threshold of 10 million rubles applies individually to each depositor and not to all foreign creditors of the bank in aggregate (which had previously given rise to a number of differing interpretations). Consequently, if obligations to a particular depositor in a calendar month do not exceed 10 million rubles, the special procedure under the Decree No. 95 does not apply.
- If the threshold of 10 million rubles is exceeded, the obligations are fulfilled by crediting funds to a type "C" account. The use of funds from such an account is only possible for permitted purposes or on the basis of a special permit from the Government Commission.
- The Decree applies exclusively to obligations under bank deposit agreements. Obligations under bank account agreements and correspondent account agreements do not fall within its scope.
- In case of early or scheduled repayment of a deposit, as well as interest payments, the special procedure applies. However, prior to the date for performance, the bank is not obliged to change the status of the deposit (e.g., convert it into a type "C" account). The extension of a deposit agreement is permitted; however, interest payments made upon renewal are subject to the requirements of the Decree No. 95.
We will be glad to answer your questions and help you understand the regulatory framework applicable to your specific issue.
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Swilar expert spoke at the CFO Conference in St. Petersburg on tax optimisation
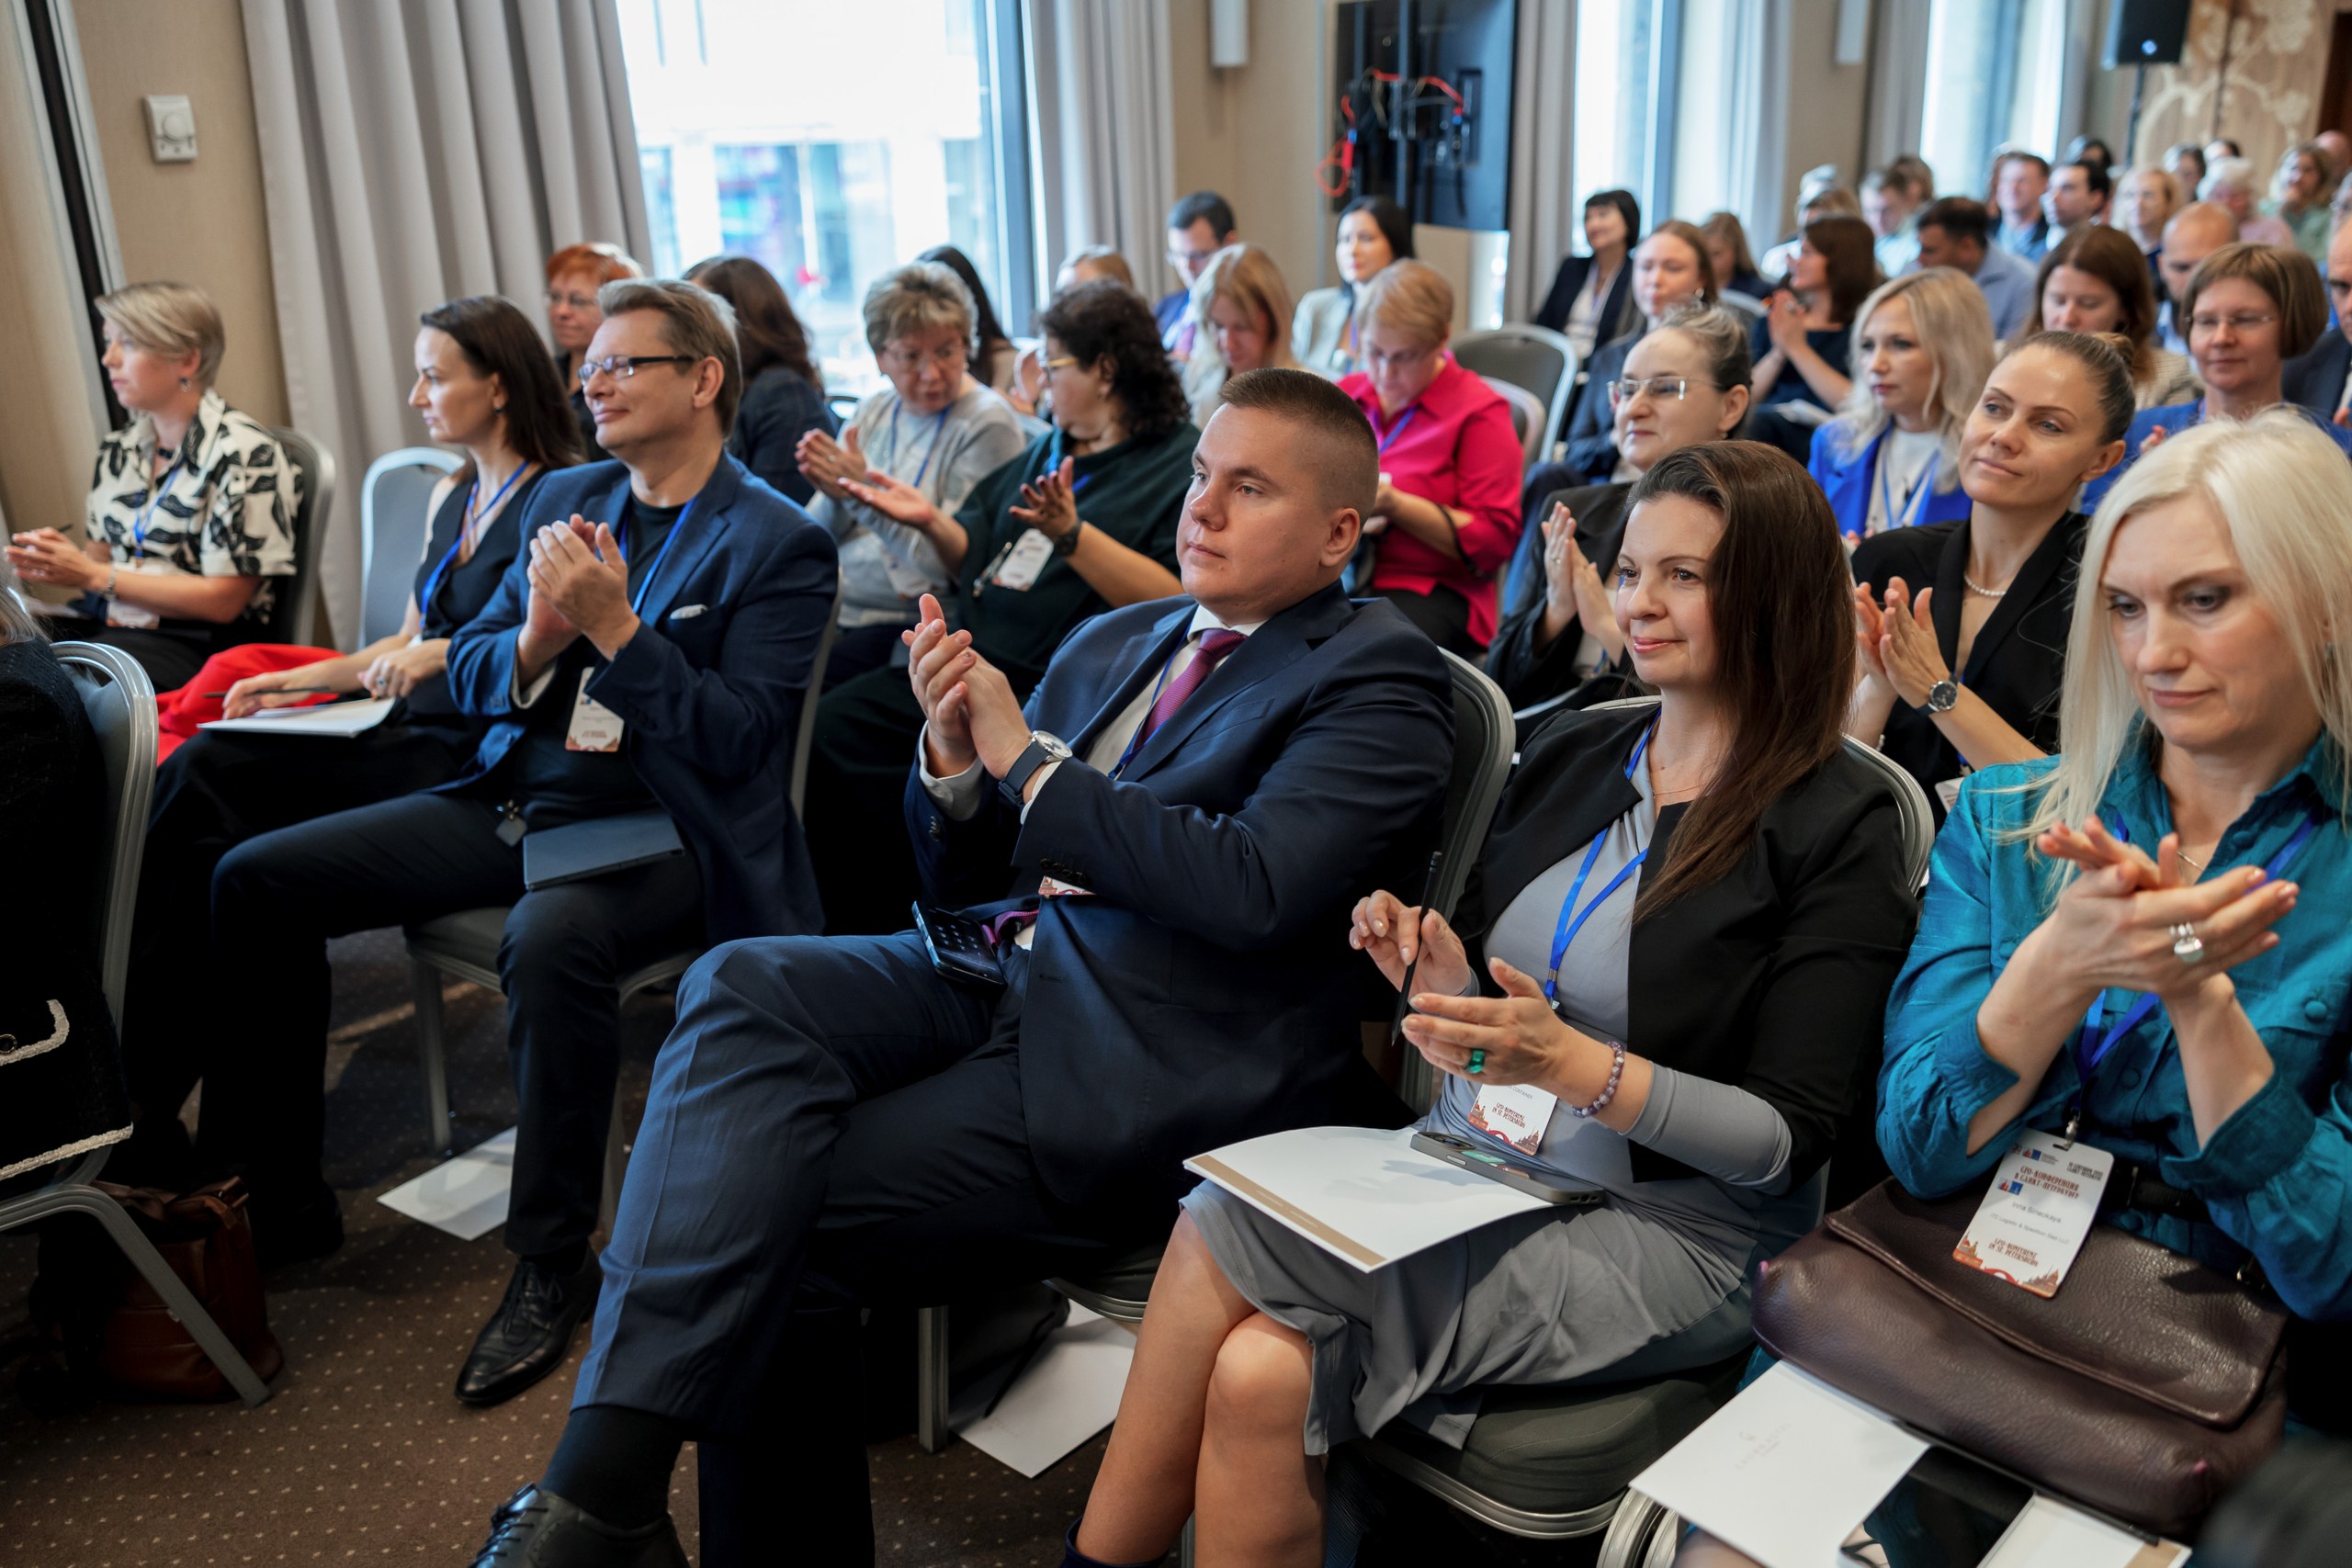
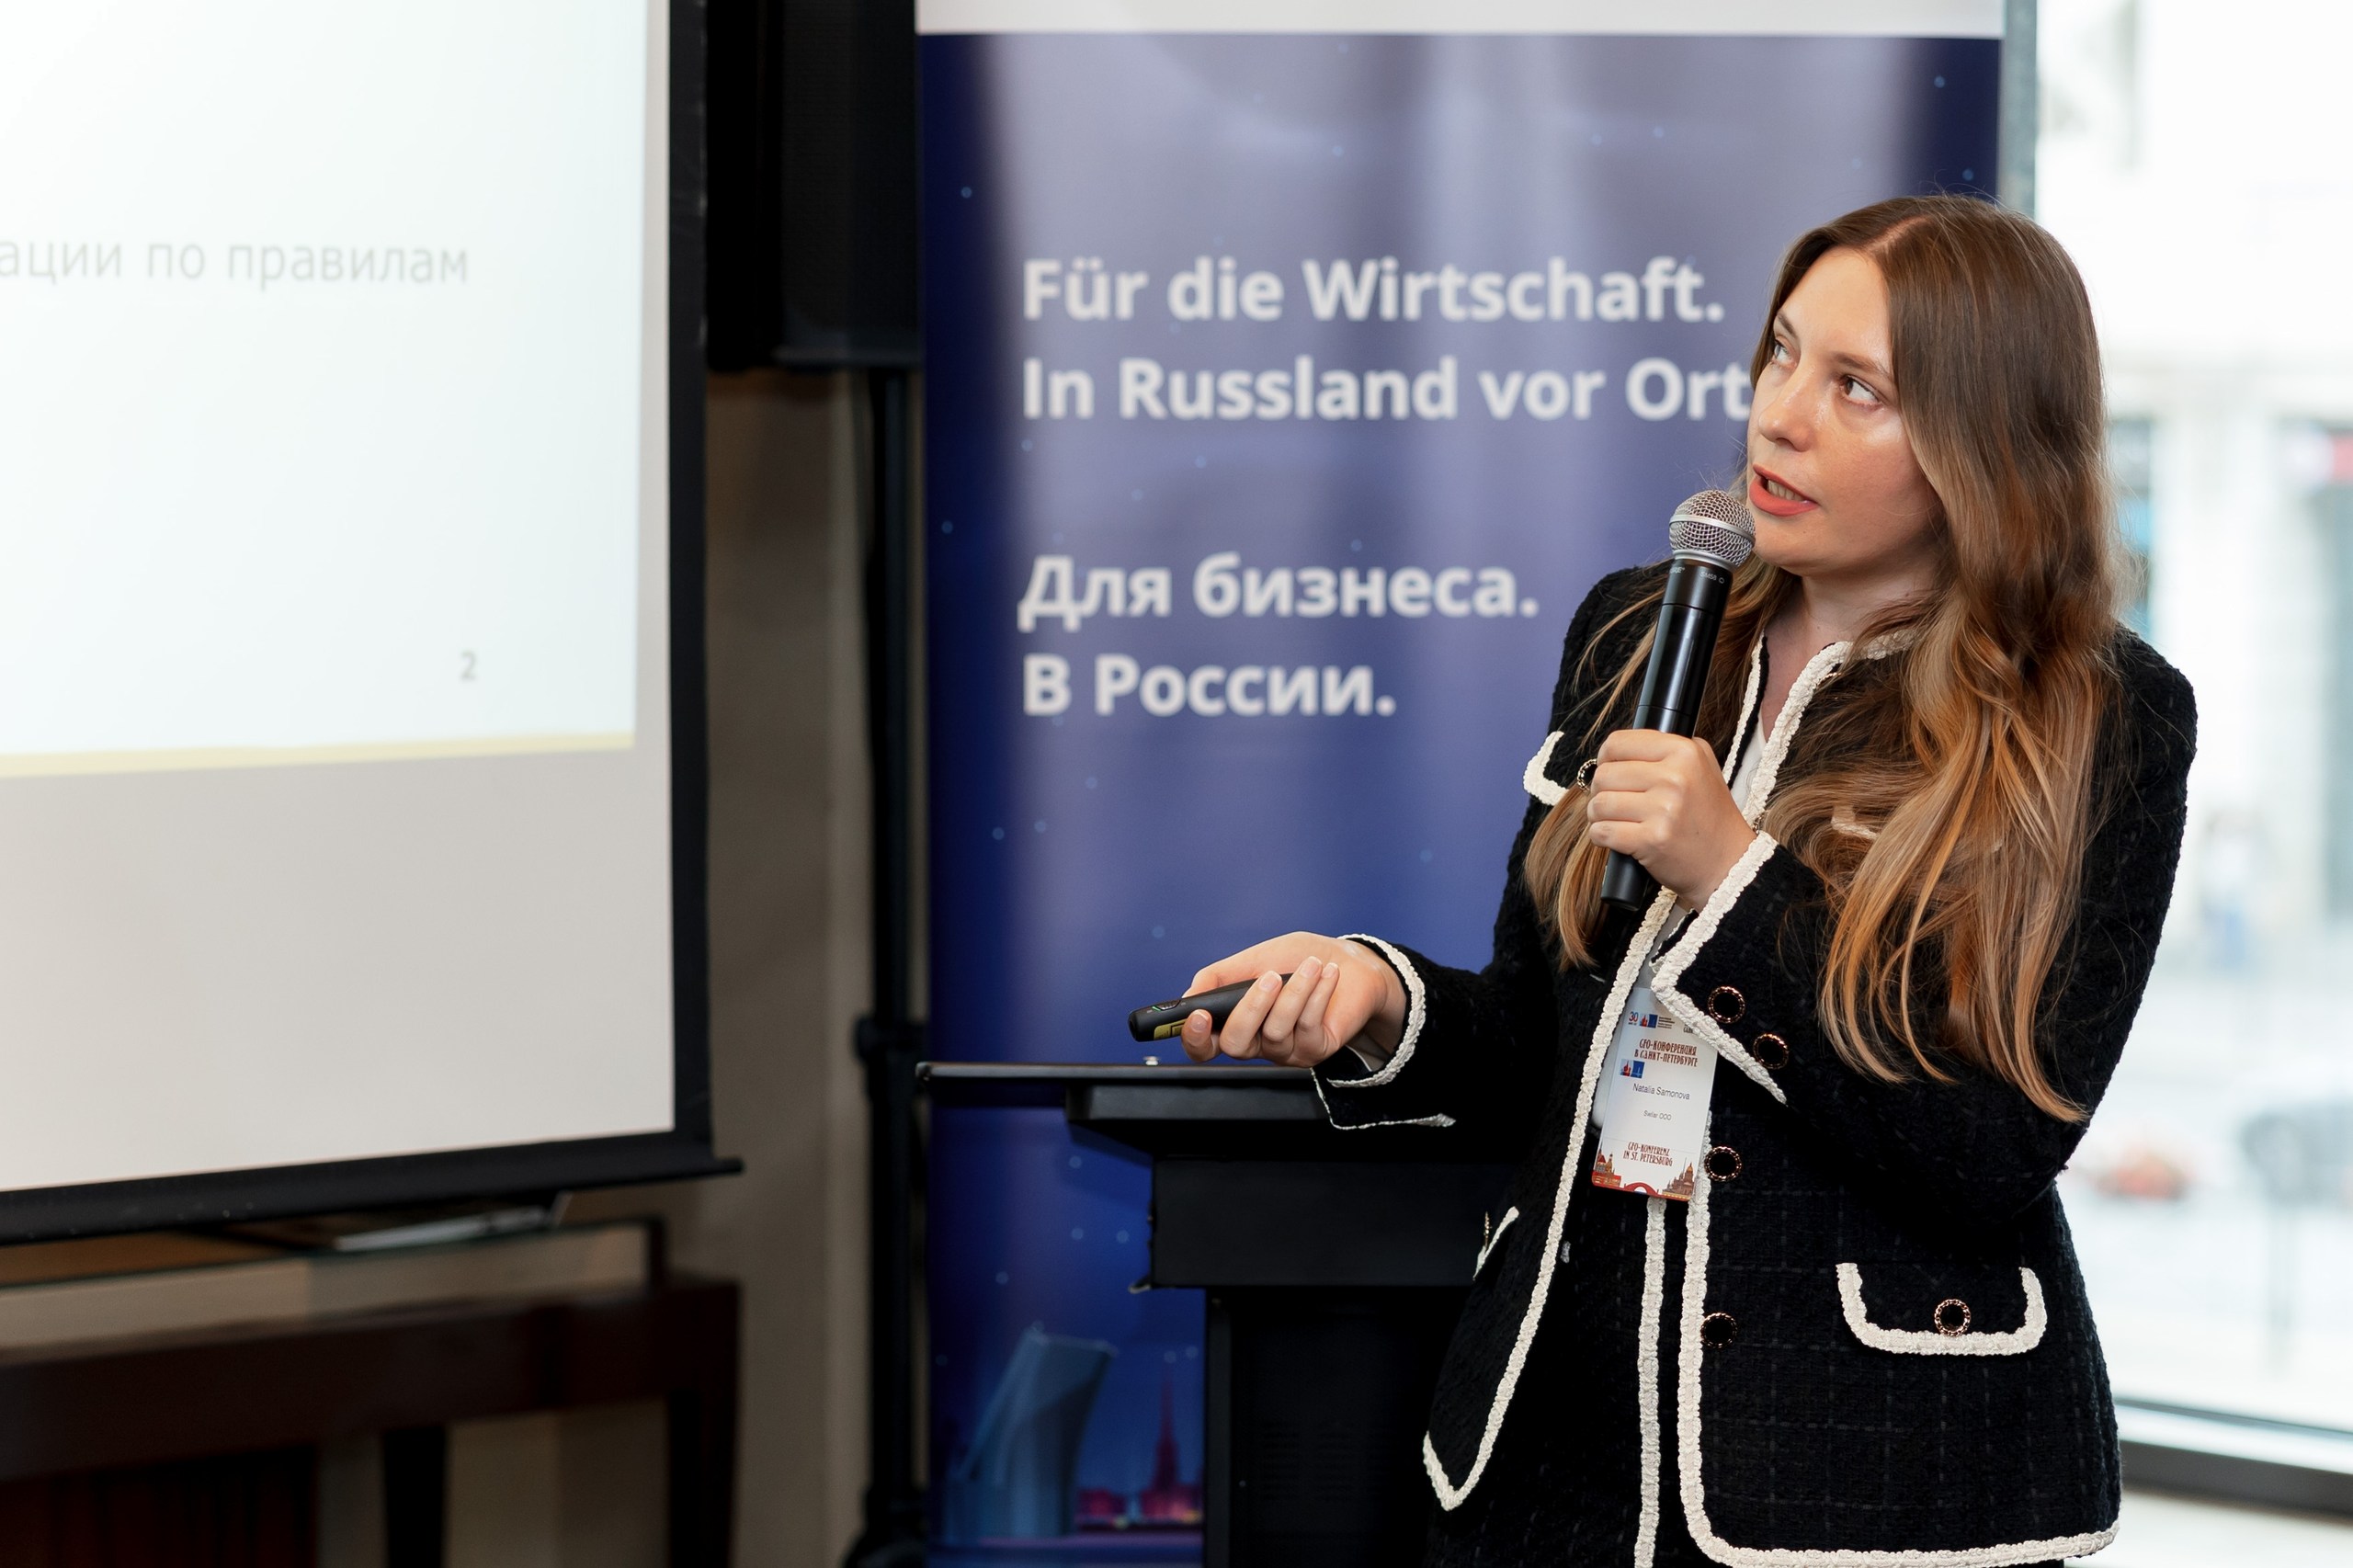
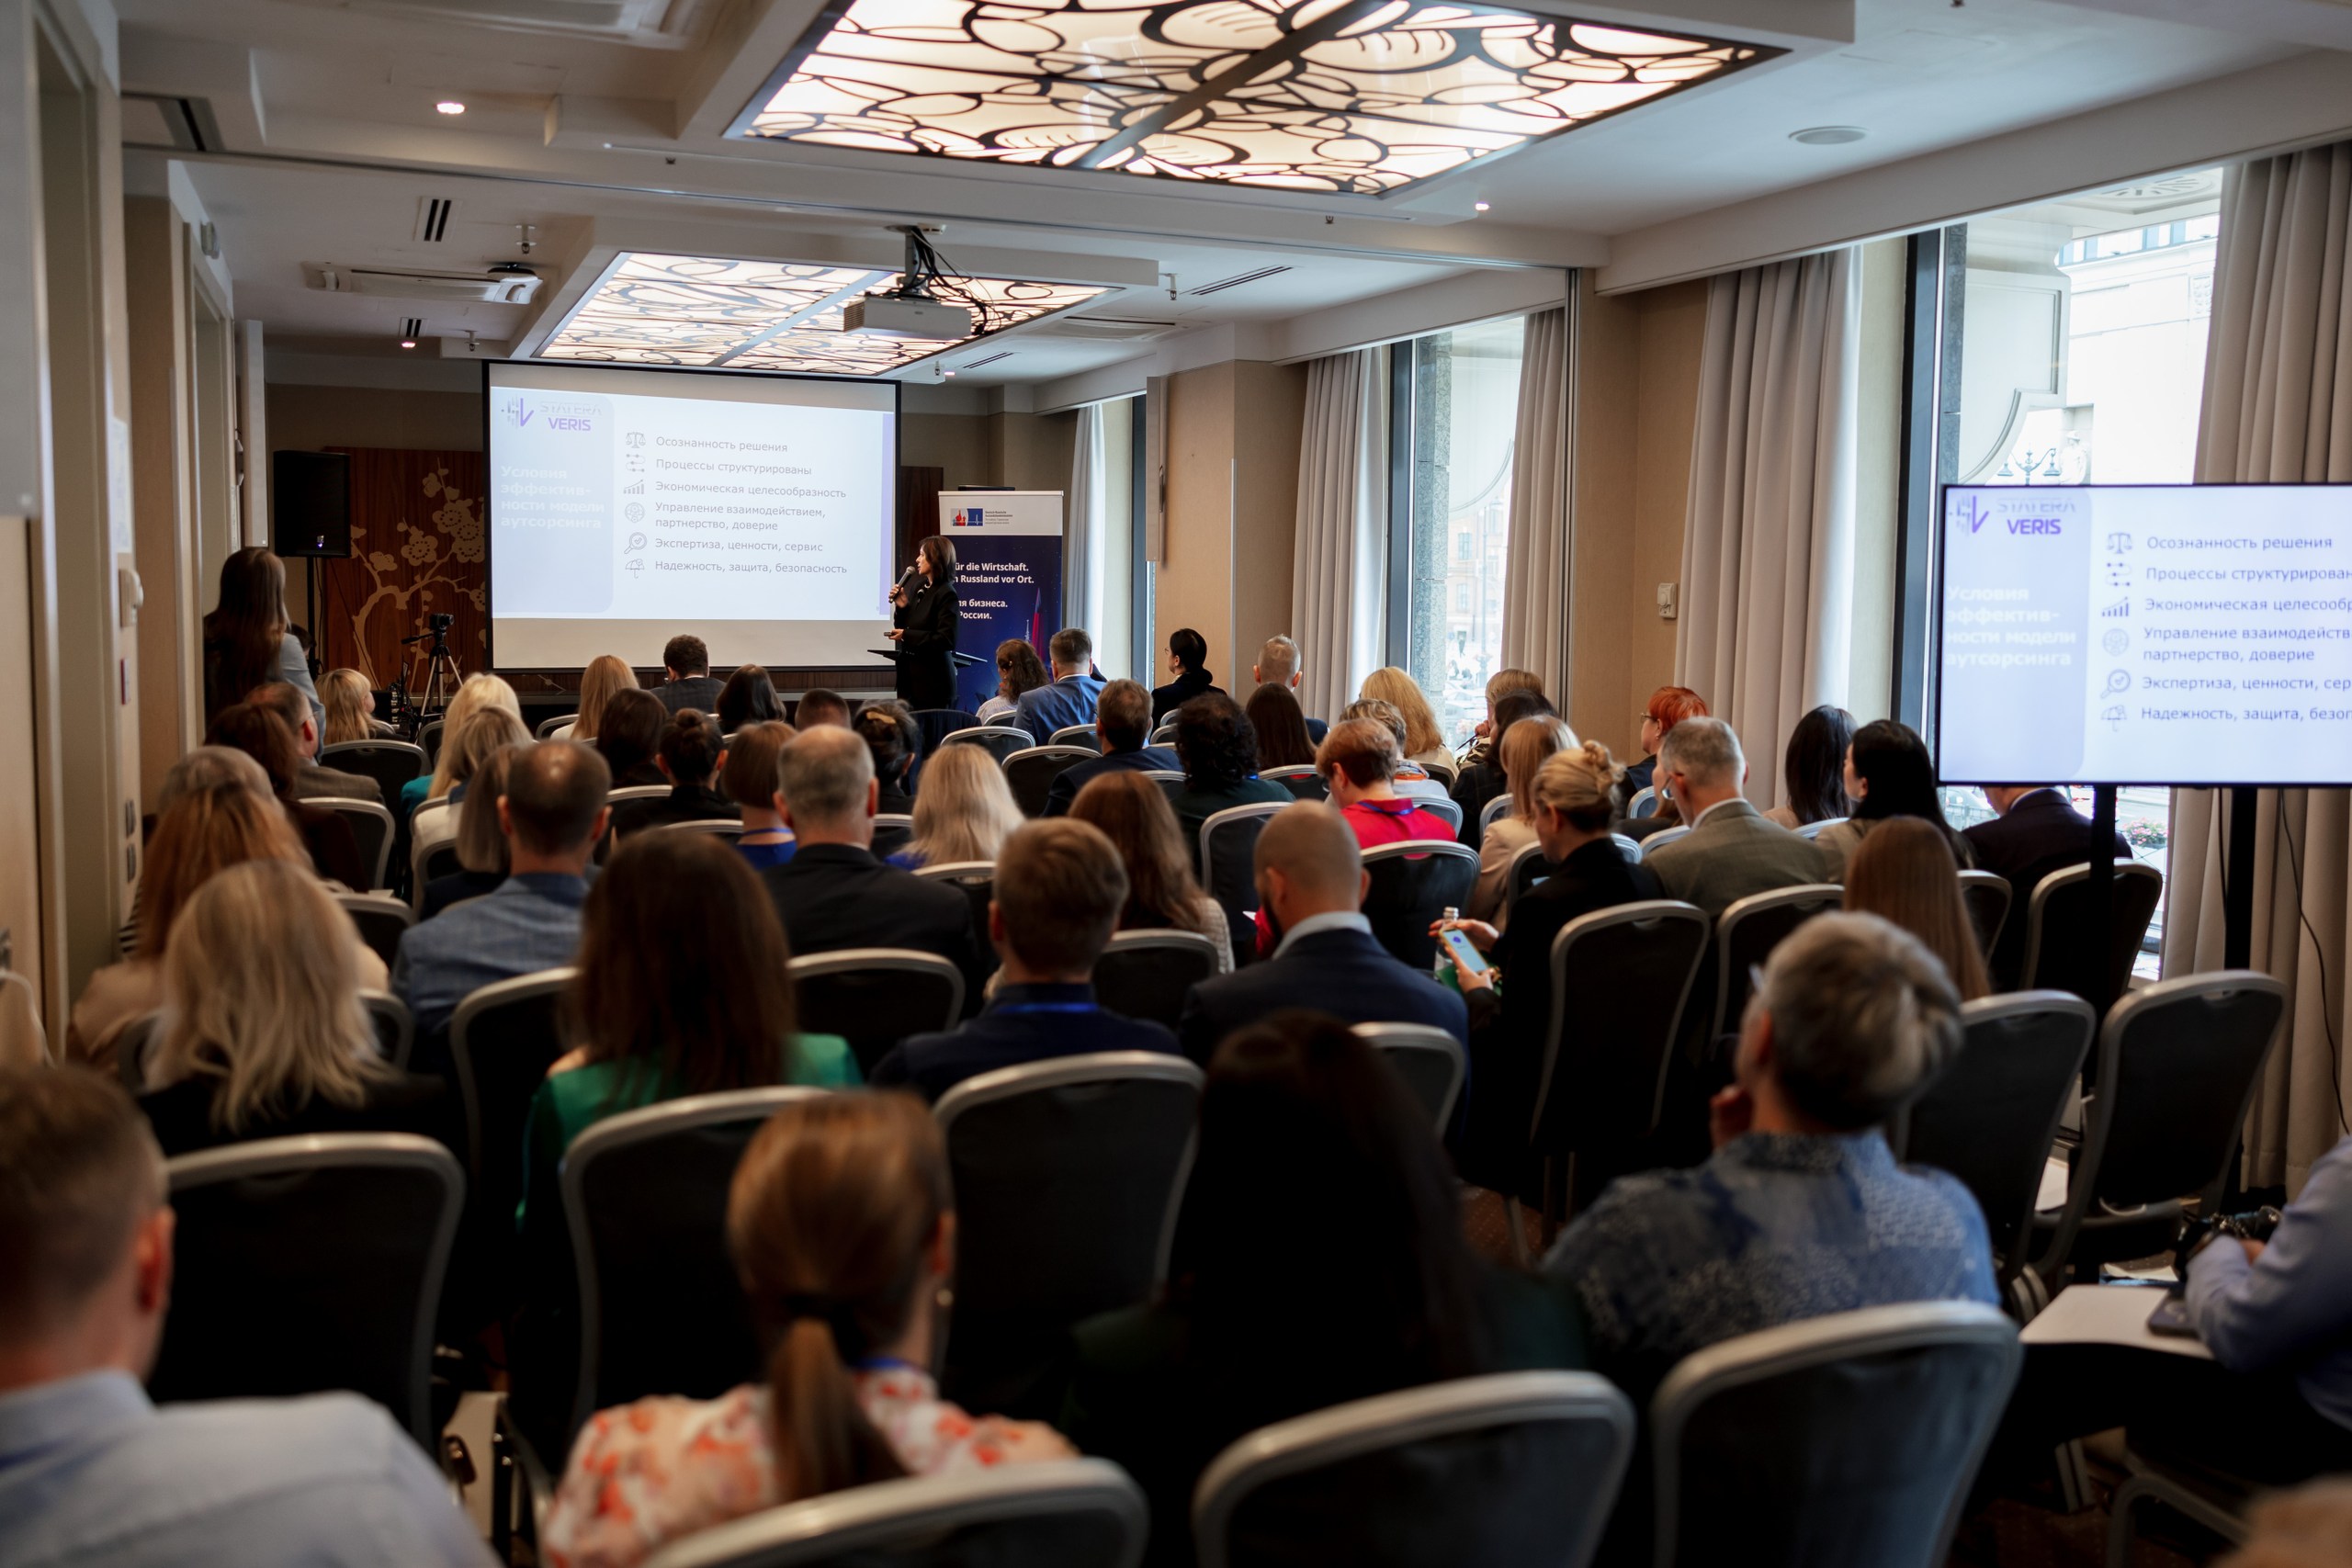
At the end of September, St. Petersburg hosted a CFO Conference that brought together finance directors and senior executives to discuss current issues in financial management. Swilar was represented by Natalia Samonova, Head of Controlling Projects, who delivered a talk on tax optimisation and government support for business.
Natalia covered lawful methods to reduce the tax burden and leverage state support measures, highlighted typical mistakes companies make when modelling tax expenses, and shared practical optimisation techniques, with special attention to criteria for choosing an effective tax regime.
A separate section of the presentation focused on opportunities offered by Special Economic Zones (SEZs) and Territories of Advanced Development (TADs). The expert outlined available tax incentives, entry conditions, and key pitfalls to consider.
In conclusion, Natalia Samonova emphasized there is no one-size-fits-all solution in tax optimisation: “An effective structure is the one that best matches a company’s specific goals and parameters.” She demonstrated approaches to assessing efficiency with illustrative calculations.
Swilar has many years of expertise in financial advisory and cost-management systems, including practical experience with SEZs and TADs. If you need assistance in selecting the optimal tax regime or evaluating the potential of government support for your business, we will be glad to advise you.
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Notice of participation in an international group of companies: procedure and deadlines
Dear colleagues,
This is a reminder that the deadline for submitting Notice of Participation in an International Group of Companies (hereinafter, the “IGC”) is August 31, 2025, for groups whose financial year coincides with the calendar year.
Filing the notice is an obligation for Russian organizations and foreign companies that recognize themselves as tax residents of Russia, which are part of an IGC and meet the criteria defined in article 105/16-1 of the RF Tax Code.
Below, we detail the key requirements, deadlines, and content of this notice.
1. The notice must be submitted by all IGC participants that are taxpayers in Russia, except for foreign organizations that only receive income specified in article 309 of the RF Tax Code (e.g., dividends, interest on debt obligations, etc.).
2. Exemption from the obligatio
Exemption from the obligation to file the notice is provided in the following cases:
 If the IGC’s parent company or the appointed participant (which are Russian entities or foreign companies that have recognized themselves as tax residents of the Russian Federation) has already filed a notice containing information about all group participants.
If the notice has been filed by another IGC participant (a Russian entity or a foreign entity that has voluntarily recognized itself as a tax resident of the RF), which has been assigned this obligation by the parent company or a non-resident appointed participant.
3. Filing deadline
The notice must be submitted electronically no later than eight months from the end of the reporting period of the IGC’s parent company (article 105.16-2 of the RF Tax Code). For example, if the reporting period ends on December 31, the filing deadline is August 31 of the following year.
4. Content of the notice
The notice must include the following information as of the end of the reporting period:
Name, OGRN (Primary State Registration Number), INN (Tax Identification Number), KPP (Tax Registration Reason Code) of each IGC participant.
Participant status (whether the filer is the parent company or the appointed participant).
Details of the parent company: name, country of tax residency, registration and tax codes, address.
Details of the appointed participant (if applicable): similar to the data required for the parent company.
Grounds for submitting the notice on behalf of all IGC participants.
End date of the reporting period.
5. Notice format
Notices must be submitted to the tax authorities electronically in XML format, in accordance with the current form established by Order No. ММВ-7-17/124@ of the Federal Tax Service of Russia dated March 6, 2018 (as amended on July 16, 2020) “On Approval of the Format of the Notice of Participation in an International Group of Companies, the Procedure for its Completion and Submission in Electronic Form“.
6. Correcting errors in the notice
If errors or incomplete information are discovered, the taxpayer has the right to submit an amended notice. If this is done before the tax service discovers the inaccuracy, the participant is exempt from liability under article 129.9 of the RF Tax Code.
7. Liability for failure to file the notice
Failure to submit the notice by the deadline or submission of inaccurate information entails a fine of 500,000 rubles for each violation.
Practical recommendations:
Determine if your group qualifies as an IGC. To do this, check if the group meets the criteria of article 105.16-1 of the RF Tax Code: whether consolidated financial statements are prepared, whether the group’s consolidated revenue for the financial year preceding the reporting year exceeds the threshold established in the country of tax residency of the group’s parent company, and whether the group includes at least one tax resident and one non-resident of the RF;
Monitor the deadlines closely; late filing leads to fines;
Use the correct format; the notice must be submitted only electronically in the format approved by the Federal Tax Service of Russia.
Conclusio
Submitting a notice of participation in an IGC is an important responsibility of members of international groups. Compliance with the deadlines and requirements for the content of the notice will help to avoid fines and claims from tax authorities.
Submit a request
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Tax monitoring: procedure and conditions for switching to it
Dear colleagues,
In 2025, tax monitoring continues to gain popularity: approximately 740 companies from more than 20 industries already use tax monitoring, another 143 companies plan to join the project and a total of more than 13,000 companies comply with the program criteria (according to the portal https://налоговыймониторинг.рф/).
Recently, we have noticed growing interest to this topic in the business community and in this review we have compiled answers to the most frequently asked questions about the procedure and conditions for applying the tax monitoring regime.
Tax monitoring is a special form of tax control, a method of extended information exchange, whereby an organization provides the tax authority with real time access to its accounting and tax records.
What are the advantages of tax monitoring?
- this type of tax control allows you to forget about traditional audits by the Federal Tax Service.
- no penalties or fines if you follow the reasoned opinion.
- you can find out about existing errors and discrepancies identified by the Federal Tax Service in real time.
Methods of information exchange:
- providing access to the organization’s information systems;
- by telecommunication channels through an electronic document management operator (until 01.01.2026, the Article 6 of the Federal Law No. 389-FZ of 31.07.2023);
- providing access to an analytical datamart.
An organization is eligible to apply tax monitoring if it complies with all of the following criteria (clause 3 of the Article 105.26 of the Tax Code):
- the total amount of taxes for the previous year was at least RUB 80 million (VAT, excise taxes, personal income tax, income tax, mineral extraction tax, insurance contributions are added up, except for VAT and excise taxes, which are paid when goods are moved across the customs border of the EAEU);
- income according to accounting (financial statements) for the previous year is at least RUB 800 million;
- the book value of assets as of 31 December of the previous year is at least RUB 800 million.
Important: compliance with one or two conditions does not entitle a business entity to apply tax monitoring. All three conditions are to be fulfilled.
There are exceptions to every rule, so compliance with the above conditions is not required for organizations specified in the clause 3.1 of the Article 105.26 of the Tax Code of the Russian Federation:
- residents of advanced development territories (ADTs),
- participants in industrial clusters,
- residents of special economic zones,
- former members of consolidated groups of taxpayers,
- state and municipal institutions, lottery operators.
It is also important to note that on April 29, 2025 the Ministry of Finance published draft amendments to the Tax Code (02/04/01-25/00154001), which include measures to improve tax monitoring.
The Ministry of Finance experts have proposed to weaken the requirements: in order to switch to tax monitoring, it will be necessary to comply with at least one of the criteria, for example, in terms of asset value, income or the amount of taxes paid.
The switch to tax monitoring is voluntary. If your company complies with all of the above criteria, in order to participate you are to submit an application not later than September 1 of the year (clause 1 of the Article 105.27 of the Tax Code of the Russian Federatio ) preceding the year of introduction of monitoring, including:
- regulations for information exchange (Appendix No. 7, the Order of the Federal Tax Service of Russia dated 11 May 2021 No. ED-7-23/476),
- information of the related parties — organizations and individuals who directly or indirectly participate in the organization and whose share of participation exceeds 25%,
- tax accounting policy for the current year,
- documents regulating the organization’s internal control system (ICS) (Appendix No. 13, the Order of the Federal Tax Service of Russia dated 11 May 2021 No. ED-7-23/476).
Until November 1 inspectors review the materials received and decide whether to perform tax monitoring or to refuse it, indicating the reasons for the refusal. Possible reasons for refusal are specified in the clause 5 of the Article 105.27 of the Tax Code of the Russian Federation, in particular:
- non-provision of documents or submission of incomplete documents by the organization;
- non-compliance by the organization with the monetary criteria (the Article 105.26 of the Tax Code of the Russian Federatio );
- non-compliance of the information exchange regulations with the established form and requirements (Appendix No. 7, Order of the Federal Tax Service of Russia dated 11 May 2021 No. ED-7-23/476);
- non-compliance of the internal control system used by the organization with the established requirements for the internal control system (Appendix No. 13, Order of the Federal Tax Service of Russia dated 11 May 2021 No. ED-7-23/476).
In conclusion we should note, that in tax monitoring interaction takes place in real time and remotely instead of traditional audits. The company itself provides the tax authority with access to its accounting data.
This simplifies interaction with the Federal Tax Service, minimizes the risks of fines, penalties and additional charges. In addition, the company receives public recognition as a conscientious taxpayer and access to qualified support in complex tax issues. At the same time the company is obliged to be fully prepared to perform its activities openly and transparently and to comply with all reasonable opinions of the inspectors.
In the following reviews we plan to focus in more detail on various aspects of tax monitoring.
We will be glad to answer any questions you may have.
Submit a request
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Prior period expenses for income tax purposes
Dear colleagues,
we would like to inform you of the planned changes in the tax accounting which are expected in the nearest time.
As a general rule, according to the Article 54 of the Tax Code of the Russian Federation, if in the current tax period expenses relating to past periods are identified, they can be recognized in the current period.
However, according to the position of the Ministry of Finance, reflected in the Letter dated 15.05.2025 № 03-03-06/1/47786, the expenses of previous years cannot be recognized in the calculation of income tax for the current period if in the previous period the tax rate was lower as this will lead to an artificial understatement of current tax liabilities. Where errors (misstatements) in the calculation of the tax base relating to previous tax (accounting) periods are identified in the current tax (accounting) period, the tax base and the amount of tax should be recalculated for the period in which these errors (misstatements) were made.
The position of the Ministry of Finance is also confirmed by the latest bill 02/04/01-25/00154001, which amends the Article 54 of the Tax Code of the Russian Federation. The bill completes the Article 54 of the Tax Code with a provision prohibiting the recognition of expenses of previous periods in the current period if the tax rate of the current period is higher than the rate applicable in the period to which the errors relate.
With great probability the bill will be adopted in the nearest time, in such case the approach described by the Ministry of Finance will be established at the level of the Tax Code of the Russian Federation.
The planned date of coming into force of the amendments to Article 54 of the Tax Code of the Russian Federation is 1 January 2026. At the moment, when the amendments have not yet come into force, we recommend to follow the approach set out in the letter of the Ministry of Finance of Russia and include all expenses relating to periods earlier than 01.01.2025 in the adjusted declaration, rather than recognize them in the current period.
We will be glad to answer questions arising from the specified changes.
Submit a request
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Сhanges in transfer pricing and notifications of controlled transactions
Dear colleagues,
A year earlier we have informed you of major changes in transfer pricing effective from 01.01.2024 (link). We kindly remind you the main aspects and inform of the recent innovations:
1. Withholding tax on services of foreign related parties
We kindly remind you that withholding tax of 15% shall on mandatory basis be withheld from services of foreign related parties – residents of the country with which the DTT has been suspended.
On April 7, the Ministry of Finance officially updated the list of countries with relevant information of current DTTs, in particular, the information on the termination of the DTT with the UK on its initiative was added, in which regard a separate information message was also published.
For transactions with companies from countries with continuing DTTs, it is necessary to study the terms of the international agreement.
2. New format for notification of controlled transactions
On December 28, 2024, the Federal Tax Service issued the Order No. ED-7-13/1088@ “On approval of the form, procedure for filling out and format for submitting a notification of controlled transactions in electronic form” dated December 02, 2024, and on March 13, 2025, the Tax Service issued clarifications (Letter of the Federal Tax Service of Russia dated March 13, 2025 No. ShYu-4- 13/2827@* (ШЮ-4-13/2827@) on ensuring the proper application of the Letter of the Federal Tax Service of Russia dated May 25, 2022 No. ShYu-4-13/6384@* (ШЮ-4-13/6384@).
One of the key points is that for transactions proceeded after January 01, 2024, the taxpayer is to specify in the notification of controlled transactions (and in the documentation submitted at the request of the Federal Tax Service of Russia or in accordance with the paragraph 8 of the Article 105.15 of the Code) the applied transfer pricing method (as provided for in the Chapter 14.3 of the Code or a combination thereof) used to justify the market price level in the controlled transaction.
The changes also imply the disclosure of more information about controlled transactions, including prices in transaction chains (applicable to previous purchase / subsequent sale) for certain categories of transactions (for instance, exchange goods).
We kindly remind that for transactions proceeded in 2024, the notification in the new format is to be submitted not later than on May 20, 2025.
Non-submission by a tax payer to the tax authority within the prescribed time limits a notification of controlled transactions proceeded within one calendar year, or submission by a taxpayer to the tax authority of a notification of controlled transactions including unreliable information, shall entail a fine of RUB 100,000. Non-submission by a taxpayer to submit documentation regarding a specific transaction (group of similar transactions) within the prescribed time limits shall entail a fine of RUB 500,000.
3. Verification of transactions with a foreign “unrelated” counterparty
We kindly remind that since January 1, 2024, transactions with “unrelated” companies registered in countries in the offshore zones list may be automatically classified as controlled transactions for transfer pricing purposes (since July 1, 2023, the list of offshore zones was expanded to 91 jurisdictions by the Order of the Ministry of Finance of Russia dated June 05, 2023 N 86n and includes, for example, the countries of the European Union, Great Britain, Japan, the USA).
Regardless of the actual interdependence of the parties, the transaction will be recognized as controlled transaction if the income for the calendar year exceeds the limit of RUB 120 million.
Exceptions are being made for transactions, where one of the counterparties is a resident or a tax resident of a foreign state with which the Russian Federation has a DTT, the effect of which was suspended by the Decree of the President of the Russian Federation, when:
-
transactions were concluded before March 1, 2022,
-
the procedure for determining prices and (or) pricing methods (formulas) applied in such
transactions remain unchanged after March 1, 2022,
-
transactions are not recognized as controlled transactions in accordance with the criteria i
effect as of March 1, 2022.
4. Updated list of countries which tax authorities conduct an automatic exchange of informatio
On December 20, 2024, the Federal Tax Service published an Order No. ED-7-17/915@ dated October 30, 2024 “On approval of the List of foreign states (territories) whose competent authorities automatically exchange country-by-country reporting”.
We kindly remind that the effective order of the Federal Tax Service of Russia dated December 20, 2022 No. ED-7-17/1226@ became void with the adoption of the above-mentioned document.
The current version specifies 45 countries and 10 territories with which automatic exchange is carried out, which is amended compared to the previous list in terms of the exclusio from this list of a number of “unfriendly” European countries, which have ceased to carry out automatic exchange of country-by-country reporting with the Federal Tax Service of the Russian Federation (for example, Germany, France, Luxembourg, Italy, Spain, Greece and other countries).
We kindly remind that subsidiaries – residents of the Russian Federation, which parent companies are registered in jurisdictions with which automatic exchange has ceased, may have to submit a country-by-country reporting upon request from the tax authorities.
Non-submission a country-by-country reporting within the within the prescribed time limits either submission of a country-by-country reporting including unreliable information entails a fine of RUB 100,000 for periods before 01.01.2024 and a fine of RUB 1,000,000 for periods starting from 2024 (the fine may be applied to one calendar year).
We have been working with transfer pricing for many years and are engaged in preparing documentation for our clients.
We will gladly support you in the process of preparing documentation and answer questions that arise in connection with the changes specified.
Your contacts on this topic:
Elena Kameneva
Olga Kireeva
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Regular (annual) general meeting of LLC participants
Dear Colleagues,
please note that in accordance with Article 34 of the Federal Law dated February 08, 1998 No. 14- FZ “On Limited Liability Companies” it is necessary to hold an ordinary (annual) general meeting of LLC participants in the period from March 01 to April 30, 2025 to approve the results of the previous year (annual reports and annual accounting (financial) statements).
Penalties may be imposed for failure to convene a meeting within the specified deadline. According to clause 11 of Article 15.23.1 of the Code of Administrative Offenses of the Russian Federation, unlawful refusal to convene or evasion from convening a general meeting, as well as violation of the requirements to the procedure for convening, preparing and holding general meetings of LLC participants shall entail the imposition of a fine. For officials (general directors) it ranges from 20,000 to 30,000 rubles, for legal entities – from 500,000 to 700,000 rubles.
Previously we informed you about changes in the procedure for holding meetings of participants of Russian LLCs starting March 01, 2025. We would like to remind you that the legislation establishes a prohibition on holding the ordinary general meeting of participants as an absentee meeting. During the COVID-19 pandemic, absentee voting at the annual meeting was possible, but the prohibition is now back in force.
In 2025, it is permitted to hold an annual general meeting of participants through combining absentee voting by ballot with a physical meeting (with some of participants present in person).
We will be glad to support you in preparing and holding an ordinary meeting to approve the results of the year by the general meeting of LLC participants, as well as to prepare the relevant minutes of the meeting or a resolution of the sole participant of the company.
Your contacts on this topic:
Maria Matrossowa
Nadezhda Maskaeva
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.
Information on participants of a foreign organization for 2024 – submit before 03/28/2025
Dear Clients,
please pay attention that the term for submission of information on the participants of a foreign organization for 2024 expires on March 28th, 2025.
All foreign organizations and foreign structures without formation of a legal entity registered with tax authorities in the Russian Federation are obliged to inform the tax authorities of all direct participants and beneficiaries regardless of the share of participatio , as well as of indirect participation of an individual or a public company (if their share exceeds 5%).
The above-mentioned information is to be submitted to the tax authority not later than on March 28th each year. An exception is foreign organizations that are registered with a Russian tax authority only for provision of services in electronic form.
Non-submission or late submission of the information entails a fine of RUB 50,000.
You can find our earlier publications on this issue here and here.
We will gladly support you in preparing and submitting information on the participants/beneficiaries of a foreign organization to the tax authorities.
Other news
06.10.2026
Legislative and Enforcement Practice Digest: September 2026
September 2026 developments in payments, banking, supplies, taxation, corporate law and employment. Adopted and expected changes and upcoming business deadlines.
06.10.2026
Federal Notarial Chamber Clarifies a Number of Issues Regarding the Adoption of Decisions by Participants of an LLC
28.09.2026
Daria Pogodina Spoke at the Association of European Businesses Conference
Daria Pogodina discussed the transformation of the finance function and management's expectations of accounting departments in 2026.